Transfer-pricing comparability permits fresh objections and filters where software service comparables are functionally unsuitable for arm's-length pr...
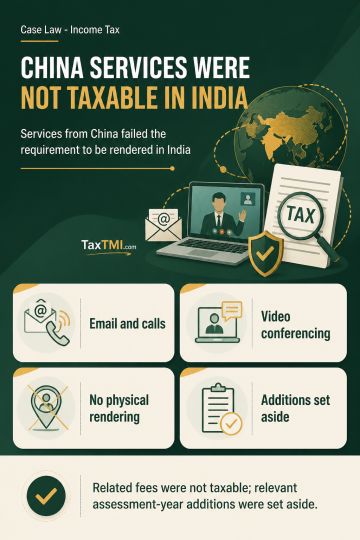
Territorial rendering requirement excludes China-based management and consultancy services from fees for technical services under the India-China DTAA...
FEMA borrowing restrictions bind charitable trusts, and civil penalties apply without proving intent for delayed repayment of non-resident rupee loans...
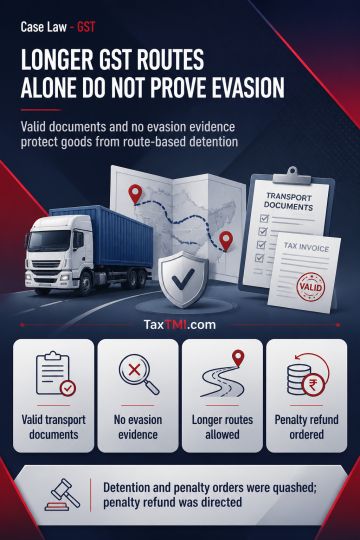
GST law does not require a transporter to declare or follow a particular route. Transporting goods by a longer route for logistical safety reasons, while carrying valid documents, does not establish mala fide intent to evade tax without material showing an intended diversion or other tax evasion. Route-based obligations under earlier VAT regimes do not apply under the GST Acts or Rules. Accordingly, detention of goods and penalty under section 129 were unsustainable solely because a longer route was used; the detention-penalty orders were quashed and refund of the penalty paid under protest was directed in accordance with law.
GST law does not require a transporter to declare or follow a particular route. Transporting goods by a longer route for logistical safety reasons, while carrying valid documents, does not establish mala fide intent to evade tax without material showing an intended diversion or other tax evasion. Route-based obligations under earlier VAT regimes do not apply under the GST Acts or Rules. Accordingly, detention of goods and penalty under section 129 were unsustainable solely because a longer route was used; the detention-penalty orders were quashed and refund of the penalty paid under protest was directed in accordance with law.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915