Reassessment for unreturned property sales survives where transfer information, non-filing, and unsupported exemption claims establish a prima facie l...
Profit-element taxation limits additions for unaccounted flat-sale receipts and grey-market purchases, while reliable search records support partial a...
Non-participating bidders cannot disturb concluded liquidation sales on speculative prejudice, while costs for such challenges must remain proportiona...
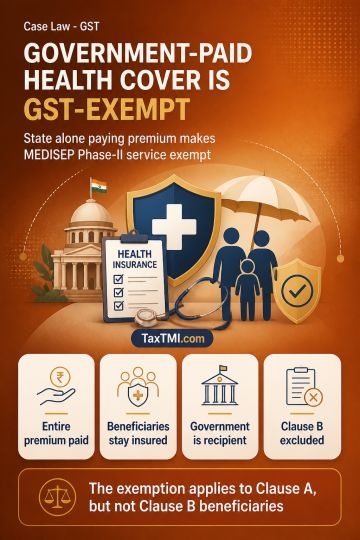
Health insurance services supplied under MEDISEP Phase-II to Clause A beneficiaries qualify for GST exemption where the State Government pays the entire premium under the insurance scheme. The State Government is the recipient of the insurance service because it alone bears the premium liability; employees, pensioners and family members remain insured beneficiaries without changing that status. The exemption under Sl. No. 40 of Notification No. 12/2017-Central Tax (Rate) is not conditional on the Government being the insured person or receiving insurance benefits. Premium received for this exempt supply is not taxable, subject to continued full Government payment. The position excludes Clause B beneficiaries.
Health insurance services supplied under MEDISEP Phase-II to Clause A beneficiaries qualify for GST exemption where the State Government pays the entire premium under the insurance scheme. The State Government is the recipient of the insurance service because it alone bears the premium liability; employees, pensioners and family members remain insured beneficiaries without changing that status. The exemption under Sl. No. 40 of Notification No. 12/2017-Central Tax (Rate) is not conditional on the Government being the insured person or receiving insurance benefits. Premium received for this exempt supply is not taxable, subject to continued full Government payment. The position excludes Clause B beneficiaries.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915