Nominee director protection shields independent financial-institution appointees from criminal liability where they lack involvement in deposit defaul...
Mandatory textile export qualifiers distinguish flame-retardant fabrics from other listed fabrics for automated identification under the textiles ince...
Page of 4915
Press 'Enter' after typing page number.
881 to 900 of 98288 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
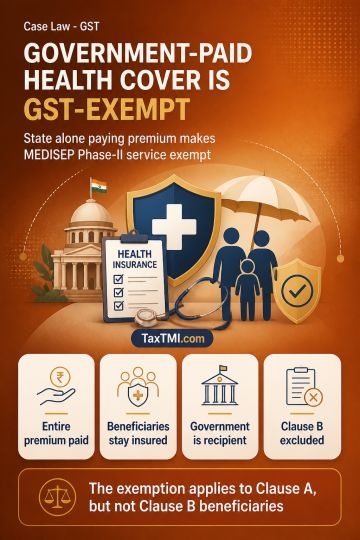
Health insurance services supplied under MEDISEP Phase-II to Clause A beneficiaries qualify for GST exemption where the State Government pays the entire premium under the insurance scheme. The State Government is the recipient of the insurance service because it alone bears the premium liability; employees, pensioners and family members remain insured beneficiaries without changing that status. The exemption under Sl. No. 40 of Notification No. 12/2017-Central Tax (Rate) is not conditional on the Government being the insured person or receiving insurance benefits. Premium received for this exempt supply is not taxable, subject to continued full Government payment. The position excludes Clause B beneficiaries.
Health insurance services supplied under MEDISEP Phase-II to Clause A beneficiaries qualify for GST exemption where the State Government pays the entire premium under the insurance scheme. The State Government is the recipient of the insurance service because it alone bears the premium liability; employees, pensioners and family members remain insured beneficiaries without changing that status. The exemption under Sl. No. 40 of Notification No. 12/2017-Central Tax (Rate) is not conditional on the Government being the insured person or receiving insurance benefits. Premium received for this exempt supply is not taxable, subject to continued full Government payment. The position excludes Clause B beneficiaries.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915