Constitutional personal-liberty safeguards limit PMLA twin bail conditions where completed investigations lead to prolonged incarceration before trial...
Automated airline software subscriptions without human intervention fail technical-services characterisation and do not make available underlying tech...
Business support recruitment and training receipts qualify for presumptive business taxation, not professional taxation under technical consultancy ru...
Treaty exemption for foreign permanent-establishment management fees prevailed, while dividend expense disallowance remained limited to an accepted al...
Page of 4915
Press 'Enter' after typing page number.
161 to 180 of 98288 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
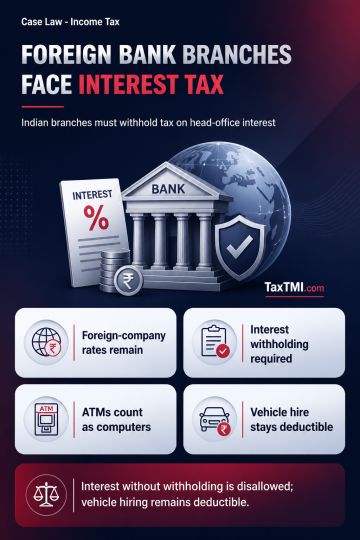
Article 24(2) of the India-Netherlands DTAA does not entitle an Indian permanent establishment of a Netherlands bank to domestic-company tax rates where it remains a foreign company; the section 90 Explanation treats a higher foreign-company rate as non-discriminatory. Article 7's separate-enterprise fiction requires consistent treatment: interest remitted by an Indian PE to its overseas head office or branches is taxable in India, requires withholding, and is disallowed if withholding fails; interest received from them is taxable PE business income. ATMs qualify as computers for depreciation based on functional utility. Accounting Standard 19 does not govern tax characterisation; vehicle hiring payments remain deductible revenue expenditure absent an intention to acquire ownership.
Article 24(2) of the India-Netherlands DTAA does not entitle an Indian permanent establishment of a Netherlands bank to domestic-company tax rates where it remains a foreign company; the section 90 Explanation treats a higher foreign-company rate as non-discriminatory. Article 7's separate-enterprise fiction requires consistent treatment: interest remitted by an Indian PE to its overseas head office or branches is taxable in India, requires withholding, and is disallowed if withholding fails; interest received from them is taxable PE business income. ATMs qualify as computers for depreciation based on functional utility. Accounting Standard 19 does not govern tax characterisation; vehicle hiring payments remain deductible revenue expenditure absent an intention to acquire ownership.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915