Interest on delayed release of requisitioned cash includes statutory pre-assessment interest and restitutionary compensation for unlawful post-assessm...
Incomplete inventory records justify rejecting accounts, while profit estimation requires relevant comparable material and interest falls under other ...
Transfer-pricing comparability requires functional alignment; delayed associated-enterprise receivables need separate LIBOR-based benchmarking, while ...
Extended reassessment limitation in search cases requires asset-linked escaped income, invalidating additions based only on unexplained money or expen...
Enhanced tolerance band under section 43CA applies retrospectively, deleting qualifying deemed-sale additions while disputed stamp valuation requires ...
Customs transaction value rejection requires communicated reasonable doubt, while written reassessment acceptance preserves challenges to enhanced val...
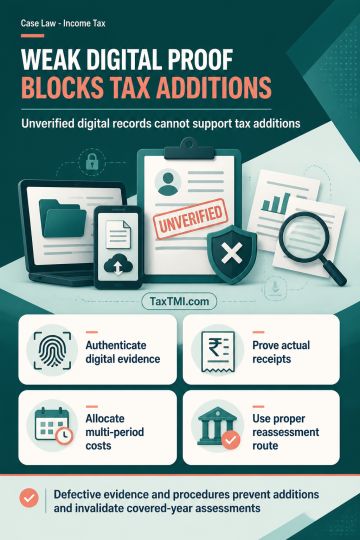
Electronic evidence lacking valid certification, proven device control, seizure records, chain of custody, hash value or corroboration cannot support income-tax additions. Digital ledger entries representing dummy, contra, adjustment or opening balances, without proof of actual receipt, do not justify unexplained-credit additions; unauthenticated WhatsApp chats alone likewise cannot establish unexplained money. Routine leased-premises repairs and annual software upgrades are revenue expenditure, whereas multi-period licence costs require apportionment under accrual and matching principles. Post-search assessments for covered preceding years must follow the prescribed reassessment procedure; use of regular scrutiny assessment is jurisdictionally defective.
Electronic evidence lacking valid certification, proven device control, seizure records, chain of custody, hash value or corroboration cannot support income-tax additions. Digital ledger entries representing dummy, contra, adjustment or opening balances, without proof of actual receipt, do not justify unexplained-credit additions; unauthenticated WhatsApp chats alone likewise cannot establish unexplained money. Routine leased-premises repairs and annual software upgrades are revenue expenditure, whereas multi-period licence costs require apportionment under accrual and matching principles. Post-search assessments for covered preceding years must follow the prescribed reassessment procedure; use of regular scrutiny assessment is jurisdictionally defective.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915