Assessing Officer jurisdiction after statutory transfer invalidates reassessment notices issued by transferor officers and nullifies resulting proceed...
Consequential appeal-effect orders must implement rectification deleting working-capital adjustments and reconsider the resulting arm's-length range c...
Discounted cash flow valuation protects share premium where projections are reasonable, while audited book expenses defeat unexplained-expenditure add...
Section 54 construction relief survives pre-transfer commencement when completion occurs within the statutory period, excluding ineligible spouse-owne...
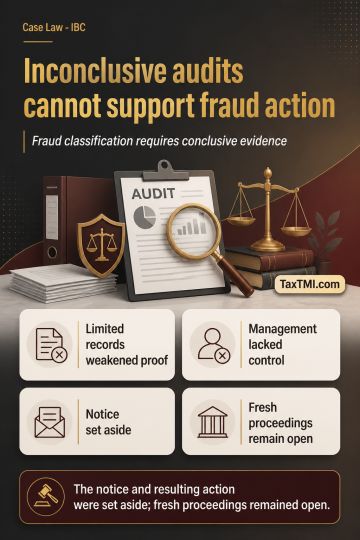
Fraud classification show-cause notices founded on inconclusive forensic audit material cannot sustain action, permitting fresh proceedings on conclus...
Page of 4913
Press 'Enter' after typing page number.
881 to 900 of 98250 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Electronic evidence lacking valid certification, proven device control, seizure records, chain of custody, hash value or corroboration cannot support income-tax additions. Digital ledger entries representing dummy, contra, adjustment or opening balances, without proof of actual receipt, do not justify unexplained-credit additions; unauthenticated WhatsApp chats alone likewise cannot establish unexplained money. Routine leased-premises repairs and annual software upgrades are revenue expenditure, whereas multi-period licence costs require apportionment under accrual and matching principles. Post-search assessments for covered preceding years must follow the prescribed reassessment procedure; use of regular scrutiny assessment is jurisdictionally defective.
Electronic evidence lacking valid certification, proven device control, seizure records, chain of custody, hash value or corroboration cannot support income-tax additions. Digital ledger entries representing dummy, contra, adjustment or opening balances, without proof of actual receipt, do not justify unexplained-credit additions; unauthenticated WhatsApp chats alone likewise cannot establish unexplained money. Routine leased-premises repairs and annual software upgrades are revenue expenditure, whereas multi-period licence costs require apportionment under accrual and matching principles. Post-search assessments for covered preceding years must follow the prescribed reassessment procedure; use of regular scrutiny assessment is jurisdictionally defective.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913