Constitutional personal-liberty safeguards limit PMLA twin bail conditions where completed investigations lead to prolonged incarceration before trial...
Automated airline software subscriptions without human intervention fail technical-services characterisation and do not make available underlying tech...
Business support recruitment and training receipts qualify for presumptive business taxation, not professional taxation under technical consultancy ru...
Treaty exemption for foreign permanent-establishment management fees prevailed, while dividend expense disallowance remained limited to an accepted al...
Centralised assessment transfers: participation after requesting centralisation can bar technical jurisdictional challenges, while assessment disputes...
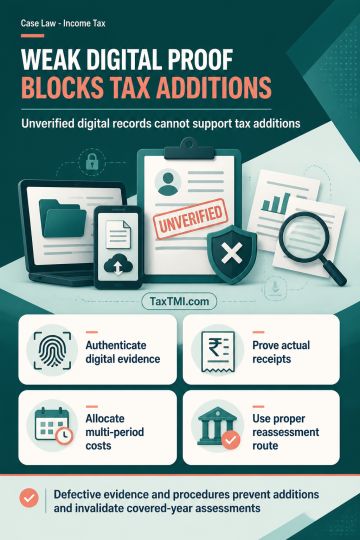
Electronic evidence lacking valid certification, proven device control, seizure records, chain of custody, hash value or corroboration cannot support income-tax additions. Digital ledger entries representing dummy, contra, adjustment or opening balances, without proof of actual receipt, do not justify unexplained-credit additions; unauthenticated WhatsApp chats alone likewise cannot establish unexplained money. Routine leased-premises repairs and annual software upgrades are revenue expenditure, whereas multi-period licence costs require apportionment under accrual and matching principles. Post-search assessments for covered preceding years must follow the prescribed reassessment procedure; use of regular scrutiny assessment is jurisdictionally defective.
Electronic evidence lacking valid certification, proven device control, seizure records, chain of custody, hash value or corroboration cannot support income-tax additions. Digital ledger entries representing dummy, contra, adjustment or opening balances, without proof of actual receipt, do not justify unexplained-credit additions; unauthenticated WhatsApp chats alone likewise cannot establish unexplained money. Routine leased-premises repairs and annual software upgrades are revenue expenditure, whereas multi-period licence costs require apportionment under accrual and matching principles. Post-search assessments for covered preceding years must follow the prescribed reassessment procedure; use of regular scrutiny assessment is jurisdictionally defective.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915