Reassessment for unreturned property sales survives where transfer information, non-filing, and unsupported exemption claims establish a prima facie l...
Profit-element taxation limits additions for unaccounted flat-sale receipts and grey-market purchases, while reliable search records support partial a...
Non-participating bidders cannot disturb concluded liquidation sales on speculative prejudice, while costs for such challenges must remain proportiona...
Page of 4916
Press 'Enter' after typing page number.
1121 to 1140 of 98302 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Section 80IA/80IB deductions were available to a new hydraulic...
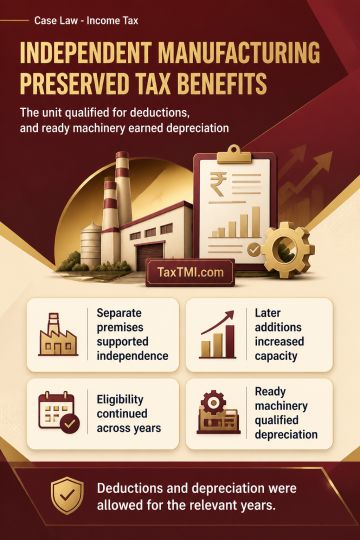
Independent manufacturing undertaking eligibility preserves Section 80IA/80IB deductions, while machinery kept ready for use qualifies for depreciation.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Section 80IA/80IB deductions were available to a new hydraulic power steering gear undertaking that operated as an integrated, independent manufacturing unit and commenced production before the statutory cut-off. Separate premises, new machinery, capital, workforce, power load, production, accounts, sales and excise records supported its independent character; subsequent machinery additions merely increased capacity. Initial-year eligibility continued through consecutive eligible years where no material facts changed. Depreciation was allowable for machinery installed and kept ready for business use, as passive use satisfies the business-use requirement where contrary evidence is absent. Deductions and depreciation were allowed for the relevant years.
Section 80IA/80IB deductions were available to a new hydraulic power steering gear undertaking that operated as an integrated, independent manufacturing unit and commenced production before the statutory cut-off. Separate premises, new machinery, capital, workforce, power load, production, accounts, sales and excise records supported its independent character; subsequent machinery additions merely increased capacity. Initial-year eligibility continued through consecutive eligible years where no material facts changed. Depreciation was allowable for machinery installed and kept ready for business use, as passive use satisfies the business-use requirement where contrary evidence is absent. Deductions and depreciation were allowed for the relevant years.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916