Section 115BBE classification requires a valid deeming-provision basis before special taxation, while the enhanced rate's temporal application remains...
Coercive recovery during GST searches is restrained pending scrutiny, preserving normal business operations and requiring adherence to investigation g...
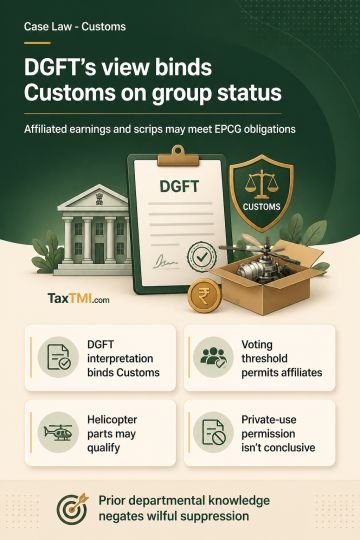
DGFT interpretation of the Foreign Trade Policy is final and binding on Customs, including whether entities qualify as group companies. Common directorial voting control meeting the prescribed threshold permits use of a group company's duty credit scrips and service-export earnings towards an importer's EPCG export obligation. Capital goods for service-sector exemptions include equipment and accessories required directly or indirectly to render services; helicopter parts used for operational transport supporting remote infrastructure projects may qualify on that basis. Aviation permission describing private use does not by itself establish personal use. Extended limitation requires deliberate non-disclosure intended to evade duty, and prior departmental knowledge negates wilful suppression.
DGFT interpretation of the Foreign Trade Policy is final and binding on Customs, including whether entities qualify as group companies. Common directorial voting control meeting the prescribed threshold permits use of a group company's duty credit scrips and service-export earnings towards an importer's EPCG export obligation. Capital goods for service-sector exemptions include equipment and accessories required directly or indirectly to render services; helicopter parts used for operational transport supporting remote infrastructure projects may qualify on that basis. Aviation permission describing private use does not by itself establish personal use. Extended limitation requires deliberate non-disclosure intended to evade duty, and prior departmental knowledge negates wilful suppression.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915