Mandatory textile export qualifiers distinguish flame-retardant fabrics from other listed fabrics for automated identification under the textiles ince...
Personal liberty safeguards restrict arrest after court-directed GST appearance, requiring interim release where authorities overreach pending proceed...
Alternative statutory remedy and delay bar GST writ challenges despite pending rectification, while distinct subject matter permits parallel proceedin...
Unverified Insight Portal Information Cannot Justify Reassessment Without a Verified Taxpayer-Specific Income-Escape Nexus or Demonstrated Application...
Page of 4913
Press 'Enter' after typing page number.
861 to 880 of 98250 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
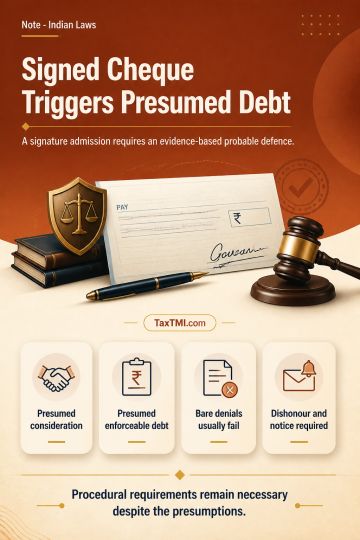
Admission of a cheque signature activates the presumptions of consideration and legally enforceable debt or liability under Sections 118(a) and 139 of the Negotiable Instruments Act. The drawer then bears an evidentiary burden to raise a probable, evidence-based defence on the preponderance of probabilities; bare denials, unsupported claims of misuse, or a blank-cheque plea ordinarily do not rebut the presumptions. Financial capacity of the complainant becomes material only after a credible and specific challenge. These presumptions do not remove the requirement to establish the procedural ingredients of Section 138, including dishonour, timely demand notice, non-payment, and timely complaint.
Admission of a cheque signature activates the presumptions of consideration and legally enforceable debt or liability under Sections 118(a) and 139 of the Negotiable Instruments Act. The drawer then bears an evidentiary burden to raise a probable, evidence-based defence on the preponderance of probabilities; bare denials, unsupported claims of misuse, or a blank-cheque plea ordinarily do not rebut the presumptions. Financial capacity of the complainant becomes material only after a credible and specific challenge. These presumptions do not remove the requirement to establish the procedural ingredients of Section 138, including dishonour, timely demand notice, non-payment, and timely complaint.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913