Blocked input tax credit for resort construction remains unavailable; interest follows actual utilisation, while delayed payment attracts statutory pe...
Duplicate PAN allocation requires record verification and deactivation reasons before assessment-related transactions can be attributed to an assessee...
Faceless assessment safeguards require requested personal hearings and adequate final show-cause response time, failing which reassessment is required...
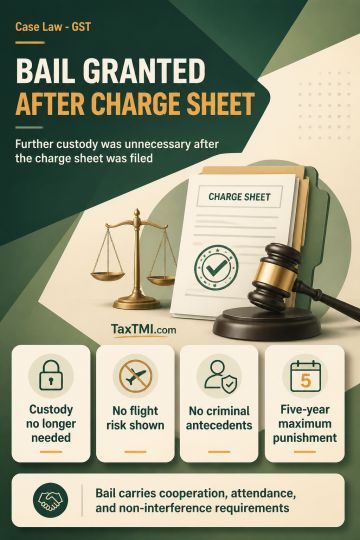
Regular bail in an alleged fraudulent input tax credit offence under the CGST Act was granted after the charge sheet was filed. Continued pre-trial detention was considered unnecessary because the accused had remained in custody, no flight risk or criminal antecedents were shown, further custodial detention was not required, and the maximum punishment was five years. Bail was subject to stringent conditions requiring cooperation in the ongoing investigation and trial involving co-accused, attendance, and non-interference with proceedings.
Regular bail in an alleged fraudulent input tax credit offence under the CGST Act was granted after the charge sheet was filed. Continued pre-trial detention was considered unnecessary because the accused had remained in custody, no flight risk or criminal antecedents were shown, further custodial detention was not required, and the maximum punishment was five years. Bail was subject to stringent conditions requiring cooperation in the ongoing investigation and trial involving co-accused, attendance, and non-interference with proceedings.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918