Duplicate PAN cancellation timeframe requires prior administrative representation before judicial intervention, ensuring a time-bound decision on the ...
Natural justice and pre-CIRP labour awards protect termination compensation, permitting withdrawal of court deposits despite later insolvency resoluti...
Arbitration of SEZ sub-lease monetary claims preserves rent, maintenance, termination, improvements and damages disputes while unused premises are vac...
Scientific research approval grants a research association tax recognition, subject to annual donor reporting, certification, and regulatory complianc...
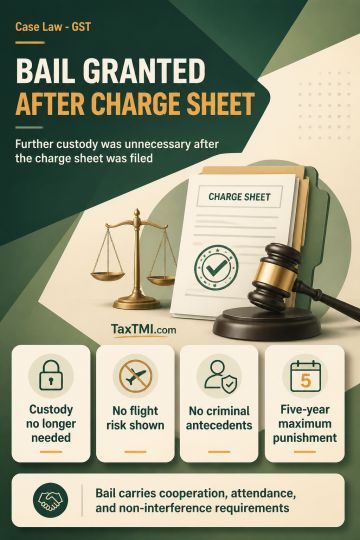
Regular bail in an alleged fraudulent input tax credit offence under the CGST Act was granted after the charge sheet was filed. Continued pre-trial detention was considered unnecessary because the accused had remained in custody, no flight risk or criminal antecedents were shown, further custodial detention was not required, and the maximum punishment was five years. Bail was subject to stringent conditions requiring cooperation in the ongoing investigation and trial involving co-accused, attendance, and non-interference with proceedings.
Regular bail in an alleged fraudulent input tax credit offence under the CGST Act was granted after the charge sheet was filed. Continued pre-trial detention was considered unnecessary because the accused had remained in custody, no flight risk or criminal antecedents were shown, further custodial detention was not required, and the maximum punishment was five years. Bail was subject to stringent conditions requiring cooperation in the ongoing investigation and trial involving co-accused, attendance, and non-interference with proceedings.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918