Appellate jurisdiction over baggage imports is excluded, requiring confiscation challenges involving passenger-carried gold to proceed by statutory re...
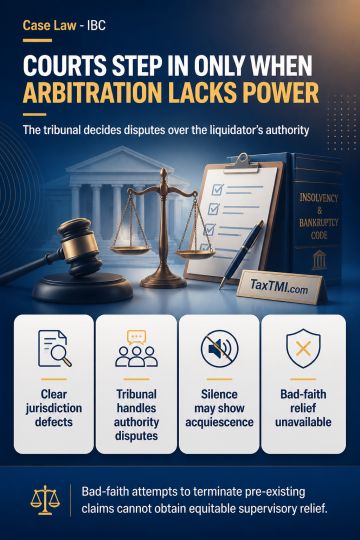
Article 227 review permits intervention in arbitration only for manifest, patent inherent jurisdictional defects, not representational authority dispu...
Page of 4918
Press 'Enter' after typing page number.
601 to 620 of 98359 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
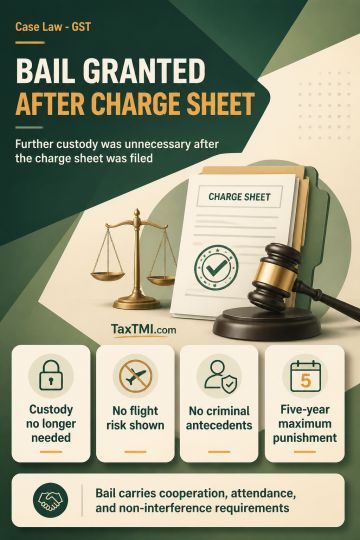
Regular bail in an alleged fraudulent input tax credit offence under the CGST Act was granted after the charge sheet was filed. Continued pre-trial detention was considered unnecessary because the accused had remained in custody, no flight risk or criminal antecedents were shown, further custodial detention was not required, and the maximum punishment was five years. Bail was subject to stringent conditions requiring cooperation in the ongoing investigation and trial involving co-accused, attendance, and non-interference with proceedings.
Regular bail in an alleged fraudulent input tax credit offence under the CGST Act was granted after the charge sheet was filed. Continued pre-trial detention was considered unnecessary because the accused had remained in custody, no flight risk or criminal antecedents were shown, further custodial detention was not required, and the maximum punishment was five years. Bail was subject to stringent conditions requiring cooperation in the ongoing investigation and trial involving co-accused, attendance, and non-interference with proceedings.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918