Transfer-pricing aggregation of distinct support-service and subcontract transactions was rejected, while debt-free receivables attracted no notional ...
Customs exemptions cover photovoltaic assembly machinery and PVF backsheets, while fully declared cleared imports may avoid confiscation and penalties...
Specific tariff classification for LCD devices overrides treatment as electricity-meter parts, defeating differential duty, extended limitation, and p...
Stayed disciplinary punishment does not establish unfitness for insolvency professional registration; reconsideration must disregard mere pendency of ...
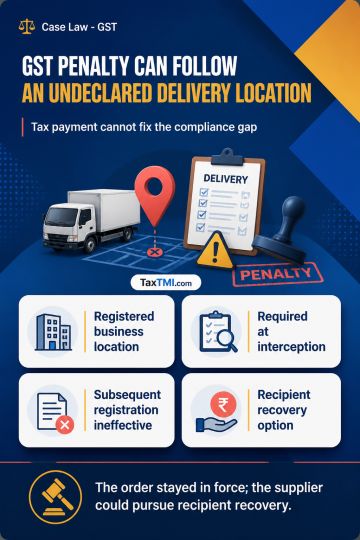
E-way bill delivery to an address not declared as the recipient's principal or additional place of business constitutes a contravention attracting penalty under Section 129, even where tax has been paid. The e-way bill tracking framework requires the declared delivery location to be a registered business address at the time of supply and interception. Subsequent registration of that location as an additional place of business does not cure the earlier contravention. The penalty order therefore remained undisturbed, while the supplier retained the option to seek recovery of the penalty from the recipient through appropriate remedies.
E-way bill delivery to an address not declared as the recipient's principal or additional place of business constitutes a contravention attracting penalty under Section 129, even where tax has been paid. The e-way bill tracking framework requires the declared delivery location to be a registered business address at the time of supply and interception. Subsequent registration of that location as an additional place of business does not cure the earlier contravention. The penalty order therefore remained undisturbed, while the supplier retained the option to seek recovery of the penalty from the recipient through appropriate remedies.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915