Embezzlement losses in charitable institutions remain allowable when misappropriation is established, irrecoverable, and not a specified-person benefi...
National long-distance undertaking status supports deduction where separately licensed infrastructure, resources, revenue, and expenditure establish c...
Agency reimbursement income follows contractual deposit-liability computation, while pending deposit collections do not constitute deemed-dividend loa...
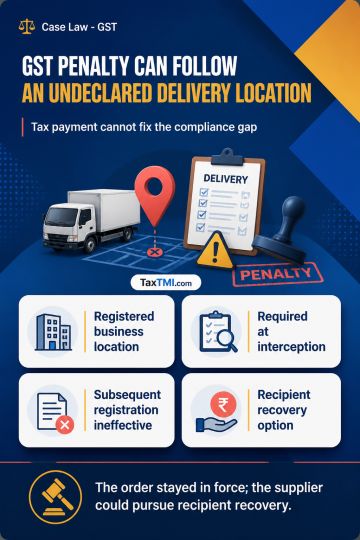
E-way bill delivery to an address not declared as the recipient's principal or additional place of business constitutes a contravention attracting penalty under Section 129, even where tax has been paid. The e-way bill tracking framework requires the declared delivery location to be a registered business address at the time of supply and interception. Subsequent registration of that location as an additional place of business does not cure the earlier contravention. The penalty order therefore remained undisturbed, while the supplier retained the option to seek recovery of the penalty from the recipient through appropriate remedies.
E-way bill delivery to an address not declared as the recipient's principal or additional place of business constitutes a contravention attracting penalty under Section 129, even where tax has been paid. The e-way bill tracking framework requires the declared delivery location to be a registered business address at the time of supply and interception. Subsequent registration of that location as an additional place of business does not cure the earlier contravention. The penalty order therefore remained undisturbed, while the supplier retained the option to seek recovery of the penalty from the recipient through appropriate remedies.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915