Blocked input tax credit for resort construction remains unavailable; interest follows actual utilisation, while delayed payment attracts statutory pe...
Duplicate PAN allocation requires record verification and deactivation reasons before assessment-related transactions can be attributed to an assessee...
Faceless assessment safeguards require requested personal hearings and adequate final show-cause response time, failing which reassessment is required...
Page of 4915
Press 'Enter' after typing page number.
681 to 700 of 98300 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
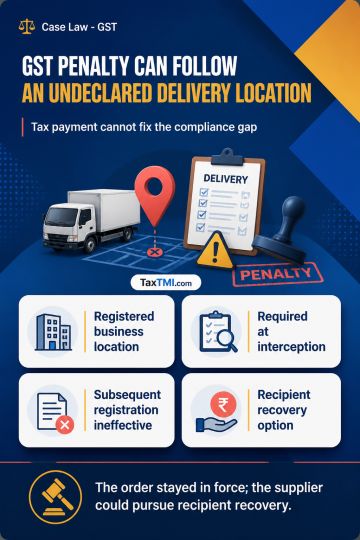
E-way bill delivery to an address not declared as the recipient's principal or additional place of business constitutes a contravention attracting penalty under Section 129, even where tax has been paid. The e-way bill tracking framework requires the declared delivery location to be a registered business address at the time of supply and interception. Subsequent registration of that location as an additional place of business does not cure the earlier contravention. The penalty order therefore remained undisturbed, while the supplier retained the option to seek recovery of the penalty from the recipient through appropriate remedies.
E-way bill delivery to an address not declared as the recipient's principal or additional place of business constitutes a contravention attracting penalty under Section 129, even where tax has been paid. The e-way bill tracking framework requires the declared delivery location to be a registered business address at the time of supply and interception. Subsequent registration of that location as an additional place of business does not cure the earlier contravention. The penalty order therefore remained undisturbed, while the supplier retained the option to seek recovery of the penalty from the recipient through appropriate remedies.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915