Head Office cost allocation requires prescribed transfer-pricing methods; treaty ceilings bar surcharge and cess, while duplicate taxation is excluded...
Cost-to-cost reimbursement of seconded employees is not service consideration; transfer-pricing markup was deleted and amalgamation amortisation allow...
Crystallisation of liability supports prior-period expense deduction, while functionally distinct divisions require separate transfer-pricing benchmar...
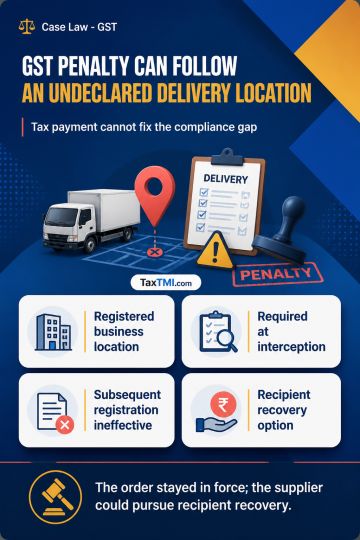
E-way bill delivery to an address not declared as the recipient's principal or additional place of business constitutes a contravention attracting penalty under Section 129, even where tax has been paid. The e-way bill tracking framework requires the declared delivery location to be a registered business address at the time of supply and interception. Subsequent registration of that location as an additional place of business does not cure the earlier contravention. The penalty order therefore remained undisturbed, while the supplier retained the option to seek recovery of the penalty from the recipient through appropriate remedies.
E-way bill delivery to an address not declared as the recipient's principal or additional place of business constitutes a contravention attracting penalty under Section 129, even where tax has been paid. The e-way bill tracking framework requires the declared delivery location to be a registered business address at the time of supply and interception. Subsequent registration of that location as an additional place of business does not cure the earlier contravention. The penalty order therefore remained undisturbed, while the supplier retained the option to seek recovery of the penalty from the recipient through appropriate remedies.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916