Transfer-pricing comparability filters require fresh arm's-length analysis, while delayed receivables need separate reconsideration with working-capit...
Section 153C jurisdiction requires timely deemed search and assessee-specific satisfaction material; otherwise reassessment must use the proper statut...
Credit-note turnover adjustments preserve inverted-duty refunds, while ministerial re-computation does not constitute an impermissible appellate reman...
Page of 4915
Press 'Enter' after typing page number.
1161 to 1180 of 98288 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
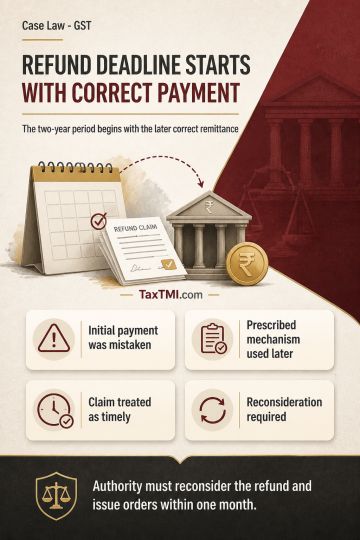
Relevant date for refund of Kerala Flood Cess mistakenly paid through GSTR-3B is the date of subsequent remittance into the correct account. Where the cess was initially paid with GSTR-3B and later deposited through the prescribed mechanism, the two-year refund limitation under Section 54 runs from the latter payment rather than the erroneous earlier payment. The refund application is therefore treated as timely, requiring the competent authority to reconsider it and issue orders within one month.
Relevant date for refund of Kerala Flood Cess mistakenly paid through GSTR-3B is the date of subsequent remittance into the correct account. Where the cess was initially paid with GSTR-3B and later deposited through the prescribed mechanism, the two-year refund limitation under Section 54 runs from the latter payment rather than the erroneous earlier payment. The refund application is therefore treated as timely, requiring the competent authority to reconsider it and issue orders within one month.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915