Discounted cash flow valuation protects share premium where projections are reasonable, while audited book expenses defeat unexplained-expenditure add...
Section 54 construction relief survives pre-transfer commencement when completion occurs within the statutory period, excluding ineligible spouse-owne...
Fraud classification show-cause notices founded on inconclusive forensic audit material cannot sustain action, permitting fresh proceedings on conclus...
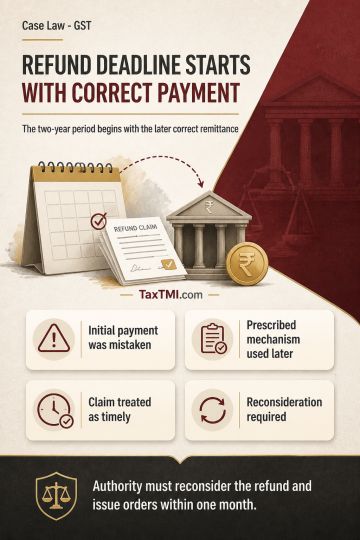
Relevant date for refund of Kerala Flood Cess mistakenly paid through GSTR-3B is the date of subsequent remittance into the correct account. Where the cess was initially paid with GSTR-3B and later deposited through the prescribed mechanism, the two-year refund limitation under Section 54 runs from the latter payment rather than the erroneous earlier payment. The refund application is therefore treated as timely, requiring the competent authority to reconsider it and issue orders within one month.
Relevant date for refund of Kerala Flood Cess mistakenly paid through GSTR-3B is the date of subsequent remittance into the correct account. Where the cess was initially paid with GSTR-3B and later deposited through the prescribed mechanism, the two-year refund limitation under Section 54 runs from the latter payment rather than the erroneous earlier payment. The refund application is therefore treated as timely, requiring the competent authority to reconsider it and issue orders within one month.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915