Mandatory textile export qualifiers distinguish flame-retardant fabrics from other listed fabrics for automated identification under the textiles ince...
Personal liberty safeguards restrict arrest after court-directed GST appearance, requiring interim release where authorities overreach pending proceed...
Alternative statutory remedy and delay bar GST writ challenges despite pending rectification, while distinct subject matter permits parallel proceedin...
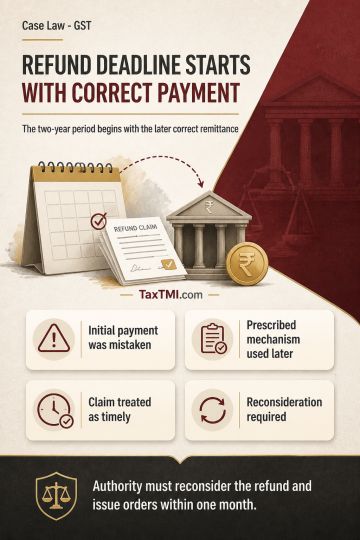
Relevant date for refund of Kerala Flood Cess mistakenly paid through GSTR-3B is the date of subsequent remittance into the correct account. Where the cess was initially paid with GSTR-3B and later deposited through the prescribed mechanism, the two-year refund limitation under Section 54 runs from the latter payment rather than the erroneous earlier payment. The refund application is therefore treated as timely, requiring the competent authority to reconsider it and issue orders within one month.
Relevant date for refund of Kerala Flood Cess mistakenly paid through GSTR-3B is the date of subsequent remittance into the correct account. Where the cess was initially paid with GSTR-3B and later deposited through the prescribed mechanism, the two-year refund limitation under Section 54 runs from the latter payment rather than the erroneous earlier payment. The refund application is therefore treated as timely, requiring the competent authority to reconsider it and issue orders within one month.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915