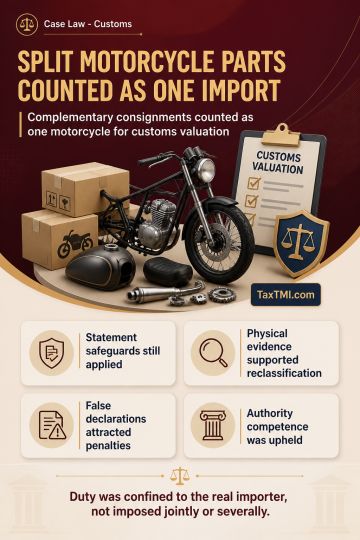
Split consignment classification treated complementary motorcycle parts as one imported motorcycle, sustaining valuation, confiscation and importer li...
Timely pronouncement of reserved judgments requires defined timelines, transparency measures, and remedial pathways to protect liberty and effective j...
Settlement-price depression requires proof of manipulation, not merely short exposure, late selling, or below-market orders, preserving disclosure pen...
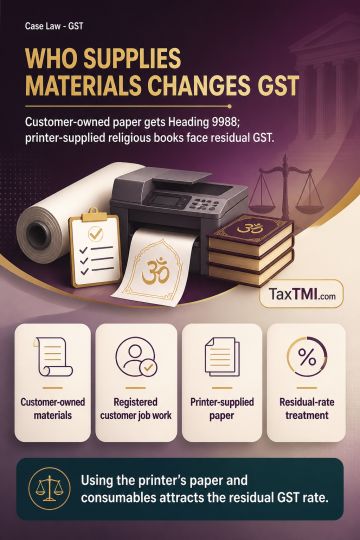
Printing on paper and content owned by a GST-registered customer constitutes job work under Heading 9988; where the customer is unregistered, it is a service of treatment or processing of goods belonging to another person under the same heading. Concessional GST treatment applies only to specified printing and to qualifying goods under Chapters 48 or 49 that themselves attract the prescribed concessional or nil rate; other printing services fall under residual entries. Printing religious books using the printer's paper and consumables is a composite supply in which printing is the principal supply. It is classifiable as a printing service under Heading 9989, rather than as a supply of printed books, and attracts the residual GST rate.
Printing on paper and content owned by a GST-registered customer constitutes job work under Heading 9988; where the customer is unregistered, it is a service of treatment or processing of goods belonging to another person under the same heading. Concessional GST treatment applies only to specified printing and to qualifying goods under Chapters 48 or 49 that themselves attract the prescribed concessional or nil rate; other printing services fall under residual entries. Printing religious books using the printer's paper and consumables is a composite supply in which printing is the principal supply. It is classifiable as a printing service under Heading 9989, rather than as a supply of printed books, and attracts the residual GST rate.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4921