Factory-consumption condition restricts solar module parts exemption and excludes imported aluminium profiles fabricated outside the production factor...
Call-recording requirements for institutional-investor client communications become non-mandatory, while institutional-investor status adopts the exis...
Restricted silver imports may clear under a valid import authorisation without additional status or exchange-routing requirements unless expressly imp...
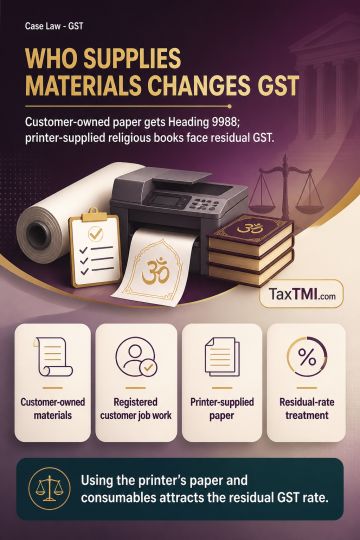
Printing on paper and content owned by a GST-registered customer constitutes job work under Heading 9988; where the customer is unregistered, it is a service of treatment or processing of goods belonging to another person under the same heading. Concessional GST treatment applies only to specified printing and to qualifying goods under Chapters 48 or 49 that themselves attract the prescribed concessional or nil rate; other printing services fall under residual entries. Printing religious books using the printer's paper and consumables is a composite supply in which printing is the principal supply. It is classifiable as a printing service under Heading 9989, rather than as a supply of printed books, and attracts the residual GST rate.
Printing on paper and content owned by a GST-registered customer constitutes job work under Heading 9988; where the customer is unregistered, it is a service of treatment or processing of goods belonging to another person under the same heading. Concessional GST treatment applies only to specified printing and to qualifying goods under Chapters 48 or 49 that themselves attract the prescribed concessional or nil rate; other printing services fall under residual entries. Printing religious books using the printer's paper and consumables is a composite supply in which printing is the principal supply. It is classifiable as a printing service under Heading 9989, rather than as a supply of printed books, and attracts the residual GST rate.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915