Business support recruitment and training receipts qualify for presumptive business taxation, not professional taxation under technical consultancy ru...
Treaty exemption for foreign permanent-establishment management fees prevailed, while dividend expense disallowance remained limited to an accepted al...
Centralised assessment transfers: participation after requesting centralisation can bar technical jurisdictional challenges, while assessment disputes...
Binding precedent remains operative despite pending challenge, supporting deletion of interest disallowance when debt is converted into preference sha...
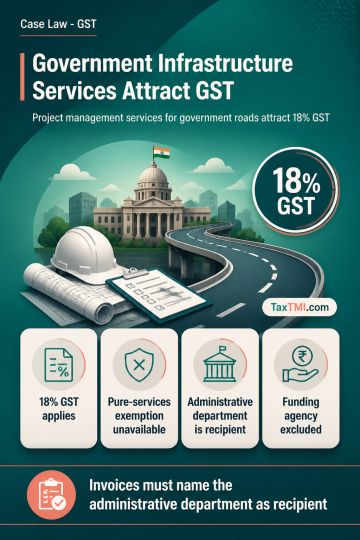
Centage-based project management services for construction projects, including project reports, technical sanctions, tendering, supervision, monitoring and coordination, are classifiable as construction project management services under SAC 998339 and taxable at 18% GST. The pure-services exemption does not apply because State and coastal highways and tourism corridor roads were not established as roads or bridges within functions entrusted to Panchayats or Municipalities. The concerned Government Administrative Department is the recipient because it owns the projects, requisitions the services and assigns implementation. A funding agency that only disburses consideration, reviews and monitors does not become the recipient; invoices must be issued to the Administrative Department.
Centage-based project management services for construction projects, including project reports, technical sanctions, tendering, supervision, monitoring and coordination, are classifiable as construction project management services under SAC 998339 and taxable at 18% GST. The pure-services exemption does not apply because State and coastal highways and tourism corridor roads were not established as roads or bridges within functions entrusted to Panchayats or Municipalities. The concerned Government Administrative Department is the recipient because it owns the projects, requisitions the services and assigns implementation. A funding agency that only disburses consideration, reviews and monitors does not become the recipient; invoices must be issued to the Administrative Department.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913