Personal liberty safeguards restrict arrest after court-directed GST appearance, requiring interim release where authorities overreach pending proceed...
Alternative statutory remedy and delay bar GST writ challenges despite pending rectification, while distinct subject matter permits parallel proceedin...
Unverified Insight Portal Information Cannot Justify Reassessment Without a Verified Taxpayer-Specific Income-Escape Nexus or Demonstrated Application...
Assessing Officer jurisdiction after statutory transfer invalidates reassessment notices issued by transferor officers and nullifies resulting proceed...
Consequential appeal-effect orders must implement rectification deleting working-capital adjustments and reconsider the resulting arm's-length range c...
Page of 4915
Press 'Enter' after typing page number.
901 to 920 of 98288 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
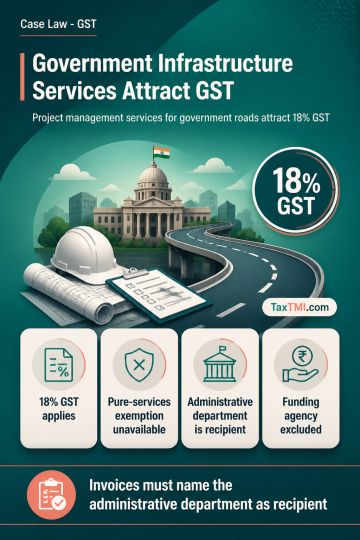
Centage-based project management services for construction projects, including project reports, technical sanctions, tendering, supervision, monitoring and coordination, are classifiable as construction project management services under SAC 998339 and taxable at 18% GST. The pure-services exemption does not apply because State and coastal highways and tourism corridor roads were not established as roads or bridges within functions entrusted to Panchayats or Municipalities. The concerned Government Administrative Department is the recipient because it owns the projects, requisitions the services and assigns implementation. A funding agency that only disburses consideration, reviews and monitors does not become the recipient; invoices must be issued to the Administrative Department.
Centage-based project management services for construction projects, including project reports, technical sanctions, tendering, supervision, monitoring and coordination, are classifiable as construction project management services under SAC 998339 and taxable at 18% GST. The pure-services exemption does not apply because State and coastal highways and tourism corridor roads were not established as roads or bridges within functions entrusted to Panchayats or Municipalities. The concerned Government Administrative Department is the recipient because it owns the projects, requisitions the services and assigns implementation. A funding agency that only disburses consideration, reviews and monitors does not become the recipient; invoices must be issued to the Administrative Department.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915