Independent manufacturing undertaking eligibility preserves Section 80IA/80IB deductions, while machinery kept ready for use qualifies for depreciatio...
Assessing Officer Satisfaction Requirement Bars Penalty for Cash Receipt in Immovable-Property Sale Cases Where Initiation Lacks Recorded Satisfaction...
Self-assessed import entries remain appealable, while bona fide classification disputes without misdeclaration cannot justify confiscation or penaltie...
Actual-user customs exemption conditions permit turnkey project transfers when imported windmill components are exclusively used for installation and ...
Customs offence disqualification excludes civil contraventions, preventing refusal of a private bonded warehouse licence based solely on monetary pena...
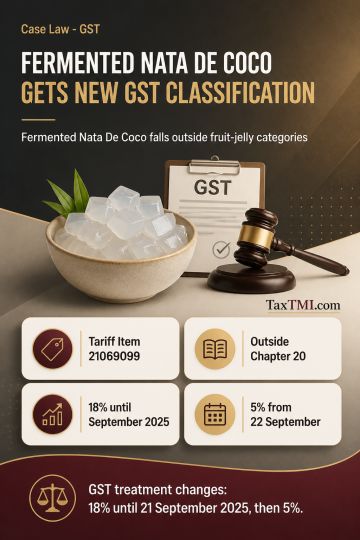
Fermented Nata De Coco is classified under Tariff Item 21069099...
Residual food-preparation classification places fermented Nata De Coco outside fruit-jelly categories, changing its GST treatment across notified periods.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Fermented Nata De Coco is classified under Tariff Item 21069099 as a food preparation not elsewhere specified or included, rather than under Chapter 20. Heading 2007 covers fruit jellies made by cooking or concentrating fruit juice or pulp with sugar, and a jelly-like appearance alone is insufficient. Microbial fermentation produces a distinct edible preparation, while Heading 2008 requires retention of the identity and essential character of an edible plant part. GST applies at 18% from 1 July 2017 to 21 September 2025 and at 5% from 22 September 2025.
Fermented Nata De Coco is classified under Tariff Item 21069099 as a food preparation not elsewhere specified or included, rather than under Chapter 20. Heading 2007 covers fruit jellies made by cooking or concentrating fruit juice or pulp with sugar, and a jelly-like appearance alone is insufficient. Microbial fermentation produces a distinct edible preparation, while Heading 2008 requires retention of the identity and essential character of an edible plant part. GST applies at 18% from 1 July 2017 to 21 September 2025 and at 5% from 22 September 2025.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4912