Coercive recovery during GST searches is restrained pending scrutiny, preserving normal business operations and requiring adherence to investigation g...
COVID-19 limitation exclusion and destination-specific e-way bills govern revisional timelines and penalties for undocumented third-party plywood deli...
Questions arising from miscellaneous application orders cannot challenge unaltered Tribunal findings, leaving the original order separately challengea...
Page of 4913
Press 'Enter' after typing page number.
1101 to 1120 of 98250 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
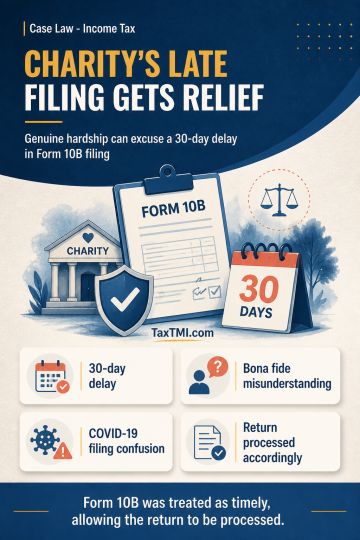
Condonation of a 30-day delay in furnishing Form No. 10B for charitable-exemption purposes may be granted under section 119(2)(b) where refusal would cause genuine hardship. Genuine hardship must be construed liberally, with substantial justice preferred over technical non-compliance, absent deliberate delay, culpable negligence or mala fides. A bona fide misunderstanding of an advanced filing due date during the COVID-19 period, coupled with filing before the extended return due date, supported condonation. A pending condonation application did not require the charitable institution to await its disposal. Form No. 10B was treated as timely filed, and the return was to be processed accordingly.
Condonation of a 30-day delay in furnishing Form No. 10B for charitable-exemption purposes may be granted under section 119(2)(b) where refusal would cause genuine hardship. Genuine hardship must be construed liberally, with substantial justice preferred over technical non-compliance, absent deliberate delay, culpable negligence or mala fides. A bona fide misunderstanding of an advanced filing due date during the COVID-19 period, coupled with filing before the extended return due date, supported condonation. A pending condonation application did not require the charitable institution to await its disposal. Form No. 10B was treated as timely filed, and the return was to be processed accordingly.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913