Capital-gains exemption for charitable trusts extends to qualifying fixed deposits, while unrecoverable TDS write-offs may constitute income applicati...
India-UK treaty characterisation of telecom-service receipts as business profits withstands unilateral domestic-law amendments for Indian tax purposes...
Transfer-pricing reimbursement adjustments require uncontrolled comparables and cannot become expense-genuineness reviews, resulting in deletion of th...
Food import sampling requirements support provisional release where unseized consignments conform to standards and raw areca classification is unestab...
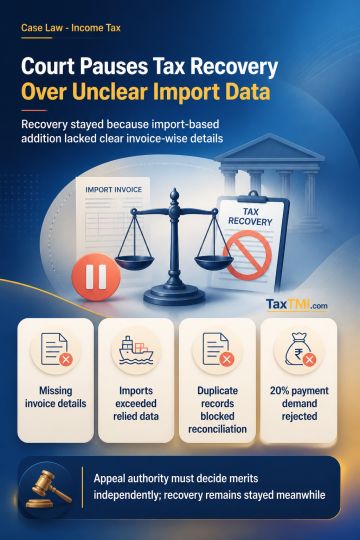
Natural justice was prima facie breached where an unexplained-expenditure addition based on import data was made without meaningful invoice-wise or bill-of-entry-wise particulars. Recorded imports supplied by the assessee exceeded the aggregate data relied on, and apparent duplication in departmental data prevented reconciliation. The High Court treated the addition as raising strong triable issues and stayed recovery pending first appeal, while requiring the appellate authority to decide independently on merits. Administrative directions concerning deposit of a prescribed demand percentage did not fetter the Court's stay power; Revenue's insistence on a 20% payment was rejected. The assessment observations remained confined to the prima facie stay determination.
Natural justice was prima facie breached where an unexplained-expenditure addition based on import data was made without meaningful invoice-wise or bill-of-entry-wise particulars. Recorded imports supplied by the assessee exceeded the aggregate data relied on, and apparent duplication in departmental data prevented reconciliation. The High Court treated the addition as raising strong triable issues and stayed recovery pending first appeal, while requiring the appellate authority to decide independently on merits. Administrative directions concerning deposit of a prescribed demand percentage did not fetter the Court's stay power; Revenue's insistence on a 20% payment was rejected. The assessment observations remained confined to the prima facie stay determination.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915