Blocked input tax credit for resort construction remains unavailable; interest follows actual utilisation, while delayed payment attracts statutory pe...
Duplicate PAN allocation requires record verification and deactivation reasons before assessment-related transactions can be attributed to an assessee...
Faceless assessment safeguards require requested personal hearings and adequate final show-cause response time, failing which reassessment is required...
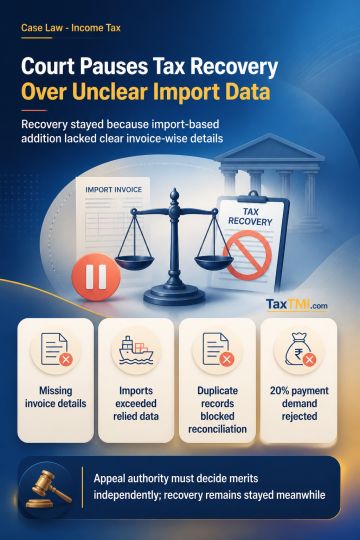
Natural justice was prima facie breached where an unexplained-expenditure addition based on import data was made without meaningful invoice-wise or bill-of-entry-wise particulars. Recorded imports supplied by the assessee exceeded the aggregate data relied on, and apparent duplication in departmental data prevented reconciliation. The High Court treated the addition as raising strong triable issues and stayed recovery pending first appeal, while requiring the appellate authority to decide independently on merits. Administrative directions concerning deposit of a prescribed demand percentage did not fetter the Court's stay power; Revenue's insistence on a 20% payment was rejected. The assessment observations remained confined to the prima facie stay determination.
Natural justice was prima facie breached where an unexplained-expenditure addition based on import data was made without meaningful invoice-wise or bill-of-entry-wise particulars. Recorded imports supplied by the assessee exceeded the aggregate data relied on, and apparent duplication in departmental data prevented reconciliation. The High Court treated the addition as raising strong triable issues and stayed recovery pending first appeal, while requiring the appellate authority to decide independently on merits. Administrative directions concerning deposit of a prescribed demand percentage did not fetter the Court's stay power; Revenue's insistence on a 20% payment was rejected. The assessment observations remained confined to the prima facie stay determination.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918