Section 115BBE classification requires a valid deeming-provision basis before special taxation, while the enhanced rate's temporal application remains...
Coercive recovery during GST searches is restrained pending scrutiny, preserving normal business operations and requiring adherence to investigation g...
COVID-19 limitation exclusion and destination-specific e-way bills govern revisional timelines and penalties for undocumented third-party plywood deli...
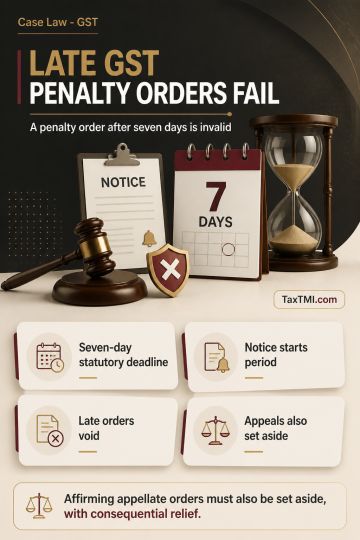
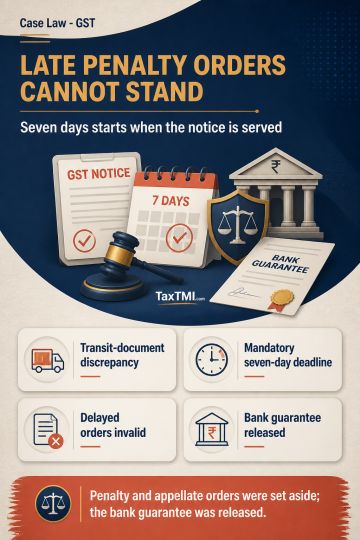
Mandatory seven-day period for passing a detention penalty order after service of notice under section 129(3) is binding because of the term "shall". A penalty order issued after that period violates the statutory time limit and vitiates the detention penalty proceedings. Such an order is void from inception and a nullity; an appellate order affirming it must also be set aside, with consequential relief.
Mandatory seven-day period for passing a detention penalty order after service of notice under section 129(3) is binding because of the term "shall". A penalty order issued after that period violates the statutory time limit and vitiates the detention penalty proceedings. Such an order is void from inception and a nullity; an appellate order affirming it must also be set aside, with consequential relief.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4920