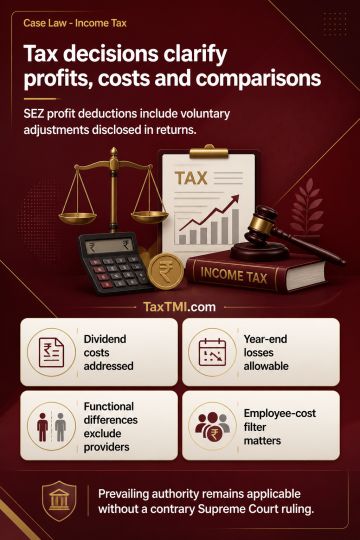
SEZ-unit profit deduction covers voluntary transfer-pricing adjustments, while exempt-income costs, foreign-exchange loss and ITeS comparables are exa...
Infrastructure-development deduction remains available to EPC contractors when substantive statutory conditions outweigh contractor labels in agreemen...
Explained Investment Sources: documented gifts and traceable salary savings supported deletion of additions for property and mutual-fund SIP investmen...
Internal comparable pricing supports arm's-length interest on compulsorily convertible debentures, preventing their recharacterisation as equity for t...
Cash deposits made during the demonetization period in bank accounts accepted as receiving business turnover cannot be selectively treated as unexplained money solely because of their timing. The deeming fiction applies only where the Revenue establishes its statutory conditions, including material linking deposits to an independent undisclosed source. Where deposits show no abnormality or disproportionality against admitted business, gross receipts cannot be assessed entirely as unexplained money; only the profit embedded in turnover is assessable. The separate addition for such deposits was deleted, while the determined business income remained undisturbed.
Cash deposits made during the demonetization period in bank accounts accepted as receiving business turnover cannot be selectively treated as unexplained money solely because of their timing. The deeming fiction applies only where the Revenue establishes its statutory conditions, including material linking deposits to an independent undisclosed source. Where deposits show no abnormality or disproportionality against admitted business, gross receipts cannot be assessed entirely as unexplained money; only the profit embedded in turnover is assessable. The separate addition for such deposits was deleted, while the determined business income remained undisturbed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916