Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ Call / WhatsApp at: +91 99117 96707

For more information, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Income Tax
  • Direct Taxes
  • Benami Property
  • Central GST Laws
  • SGST - State GST Laws
  • Customs
  • FTP - Foreign Trade Policy
  • SEZ - Special Economic Zone
  • FEMA - Foreign Exchange Management
  • Companies Law
  • SEBI - Securities & Exchange Board of India
  • IBC - Insolvency and Bankruptcy
  • Law of Competition
  • PMLA - Money-Laundering
  • Indian Laws
  • Bill / Finance Bills
  • Wealth Tax
  • Service Tax
  • Central Excise
  • VAT / Sales Tax
Month:
---- All Months ---- ❯
  • ---- All Months ----
  • January
  • February
  • March
  • April
  • May
  • June
  • July
  • August
  • September
  • October
  • November
  • December
Year:
---- All Years ---- ❯
  • ---- All Years ----
  • 2026
  • 2025
  • 2024
  • 2023
  • 2022
  • 2021
  • 2020
  • 2019
  • 2018
  • 2017
  • 2016
  • 2015
  • 2014
  • 2013
  • 2012
  • 2011
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
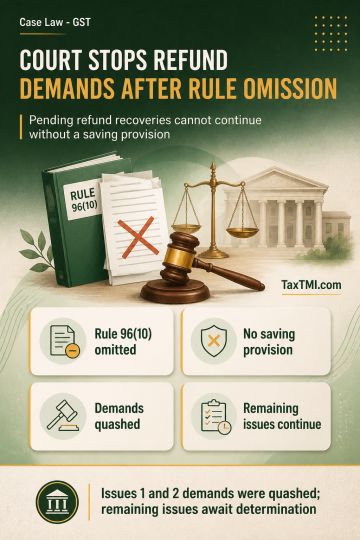
    Omission of Rule 96(10) invalidates refund-recovery demands unless a saving provision expressly preserves pending proceedings.
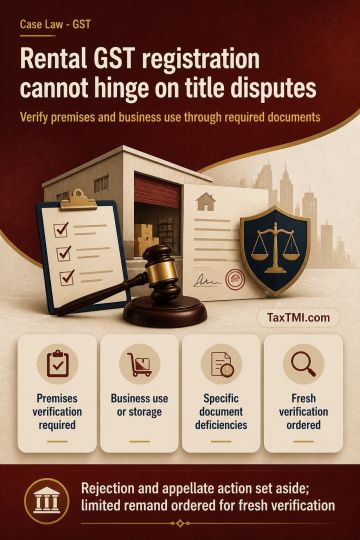
    GST registration of rented business premises cannot depend on unresolved title disputes and requires fair, document-based verification.
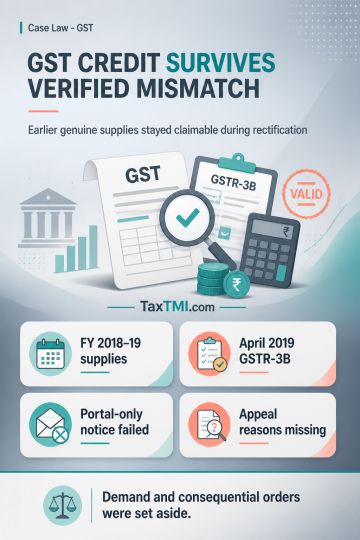
    Input tax credit mismatches cannot defeat verified prior-year supplies, while defective notice and unreasoned appeal orders fail.
    Inverted duty structure refunds cover higher-taxed tea packaging inputs, and departmental circulars cannot curtail statutory entitlement.
    Credit notes reducing taxable turnover must be deducted when calculating inverted duty structure refunds for returned or rejected supplies.
    Inverted duty refunds cover higher-taxed ancillary inputs despite common HSN classification of principal inputs and finished goods.
    Show-cause notice limits in GST registration cancellation prevent input tax credit demands through restoration conditions.
    Specified-recipient condition for GST exemption defeats sub-contracted manpower claims where services are supplied to private contractors.
    Transfer pricing turnover filters remain valid comparability criteria where market conditions, assets and risks materially differ.
    Streedhan and documented family withdrawals defeated unexplained jewellery and cash additions during search assessments in full.
    Section 148A Notice Scope Bars Reassessment Additions for Unidentified Loan-Repayment Cash Deposits After Original Deposits Were Dropped
    Recorded Escapement Requirement invalidates reassessment when unrelated share-sale income is added without assessing the recorded underpricing issue.
    Extinguishment of pre-CIRP tax claims can prevent pending income-tax appeals where claims were excluded from insolvency proceedings.
    Customs classification disputes bypass High Court appeals and must be challenged before the Supreme Court under the statutory appellate route.
    Insolvency appeal limitation begins on order pronouncement; delayed certified-copy applications cannot extend the absolute filing deadline.
    Constitutional personal-liberty safeguards limit PMLA twin bail conditions where completed investigations lead to prolonged incarceration before trial...
    Predicate FIR compromise quashing does not erase proceeds of crime, leaving statutory money-laundering bail standards fully applicable.
    Revisional jurisdiction limits prevent fresh tax claims based on facts not before the Assessing Officer after revised-return deadlines expire.
    Faceless reassessment allocation invalidates jurisdictional officer notices, while retrospective validation cannot override judicial rulings without c...
    Automated airline software subscriptions without human intervention fail technical-services characterisation and do not make available underlying tech...
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Highlights
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries

Highlights

Back

All Highlights

Showing Results for :
Reset Filters
No Records Found

Highlights

Back

All Highlights

Section 153C treats the recording of satisfaction, or receipt of...

Section 153C jurisdiction requires timely deemed search and assessee-specific satisfaction material; otherwise reassessment must use the proper statutory route.

Contents
Summary
Note

Note

-

Bookmark

Print

Print

Income Tax September 22, 2026 Case Laws AT
Section 153C treats the recording of satisfaction, or receipt of seized records by the Assessing Officer of a non-searched person, as that person's deemed search date. Where that event occurs after 1 April 2021, proceedings under section 153C(3) are unavailable and reassessment under section 147 is the applicable route. A consolidated satisfaction note must also identify assessee-specific adverse material and explain its nexus to income alleged to have escaped assessment; generic references to digital devices or electronic evidence do not satisfy this requirement.

Topics

Acts Income Tax