Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
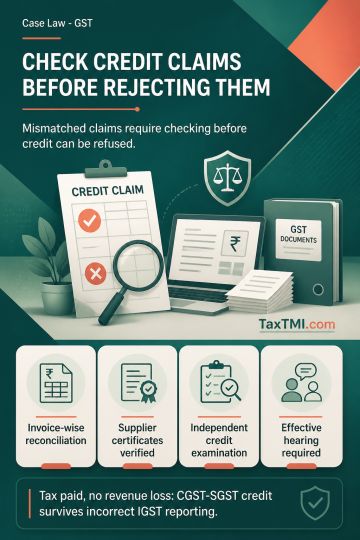
Input tax credit claimed in GSTR-3B but not reflected in GSTR-2A requires category-wise and invoice-wise reconciliation; invoices alone or supplier default do not establish entitlement, while the entire mismatch cannot be disallowed without verification. Supplier certificates may be considered under the applicable circular but must be verified, and reverse-charge credit and tax-head or B2B-to-B2C reporting errors require independent examination. Effective opportunity of hearing is required before adjudication. Renting of immovable property is supplied where the property is located; where the supplier and property are in the same State, CGST and SGST credit remains available despite erroneous IGST reporting if tax is paid and no revenue loss arises.
Input tax credit claimed in GSTR-3B but not reflected in GSTR-2A requires category-wise and invoice-wise reconciliation; invoices alone or supplier default do not establish entitlement, while the entire mismatch cannot be disallowed without verification. Supplier certificates may be considered under the applicable circular but must be verified, and reverse-charge credit and tax-head or B2B-to-B2C reporting errors require independent examination. Effective opportunity of hearing is required before adjudication. Renting of immovable property is supplied where the property is located; where the supplier and property are in the same State, CGST and SGST credit remains available despite erroneous IGST reporting if tax is paid and no revenue loss arises.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI