Anti-profiteering obligations survive business demerger, complaint withdrawal, and customized supply arrangements where rate-reduction benefits are no...
Road restoration charges constitute taxable services when requested for commercial pipeline activity, requiring reverse-charge GST from the business r...
Interest on delayed release of requisitioned cash includes statutory pre-assessment interest and restitutionary compensation for unlawful post-assessm...
Incomplete inventory records justify rejecting accounts, while profit estimation requires relevant comparable material and interest falls under other ...
Transfer-pricing comparability requires functional alignment; delayed associated-enterprise receivables need separate LIBOR-based benchmarking, while ...
Page of 4915
Press 'Enter' after typing page number.
121 to 140 of 98300 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
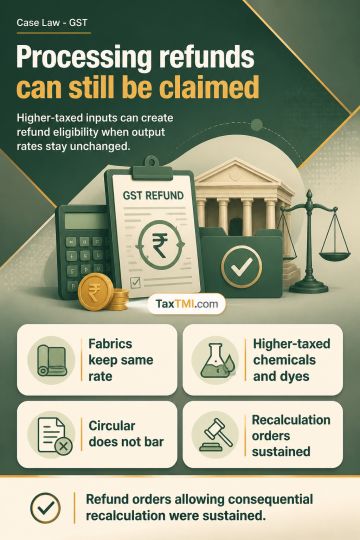
Refund of accumulated input tax credit under an inverted duty structure remains available where processed fabrics retain the same GST rate and credit accumulates from higher-taxed chemicals, dyes and consumables used in job-work processing. Circular No. 135/05/2020-GST concerns credit accumulation caused by a GST-rate reduction on the same goods and does not bar such refund claims. Once substantive refund eligibility is determined, an appellate direction for arithmetical recomputation merely implements that determination and is not a prohibited remand, provided the original authority cannot reconsider the merits. Refund orders allowing consequential recalculation were sustained.
Refund of accumulated input tax credit under an inverted duty structure remains available where processed fabrics retain the same GST rate and credit accumulates from higher-taxed chemicals, dyes and consumables used in job-work processing. Circular No. 135/05/2020-GST concerns credit accumulation caused by a GST-rate reduction on the same goods and does not bar such refund claims. Once substantive refund eligibility is determined, an appellate direction for arithmetical recomputation merely implements that determination and is not a prohibited remand, provided the original authority cannot reconsider the merits. Refund orders allowing consequential recalculation were sustained.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915