Opportunity to furnish unsecured-loan confirmations is required before reassessment initiation; proceedings require fresh consideration after taxpayer...
Under-reporting on a first reassessment return attracts penalty, while enhanced misreporting penalty requires proof of a statutory misreporting catego...
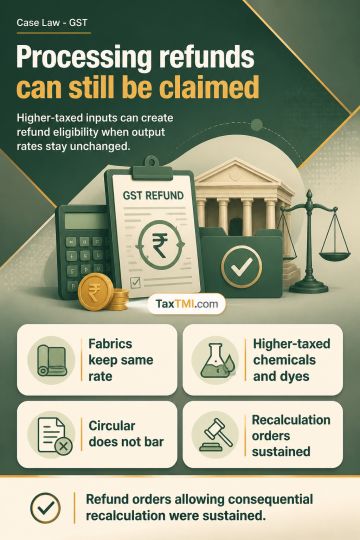
Refund of accumulated input tax credit under an inverted duty structure remains available where processed fabrics retain the same GST rate and credit accumulates from higher-taxed chemicals, dyes and consumables used in job-work processing. Circular No. 135/05/2020-GST concerns credit accumulation caused by a GST-rate reduction on the same goods and does not bar such refund claims. Once substantive refund eligibility is determined, an appellate direction for arithmetical recomputation merely implements that determination and is not a prohibited remand, provided the original authority cannot reconsider the merits. Refund orders allowing consequential recalculation were sustained.
Refund of accumulated input tax credit under an inverted duty structure remains available where processed fabrics retain the same GST rate and credit accumulates from higher-taxed chemicals, dyes and consumables used in job-work processing. Circular No. 135/05/2020-GST concerns credit accumulation caused by a GST-rate reduction on the same goods and does not bar such refund claims. Once substantive refund eligibility is determined, an appellate direction for arithmetical recomputation merely implements that determination and is not a prohibited remand, provided the original authority cannot reconsider the merits. Refund orders allowing consequential recalculation were sustained.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI