Transfer-pricing comparability filters require fresh arm's-length analysis, while delayed receivables need separate reconsideration with working-capit...
Section 153C jurisdiction requires timely deemed search and assessee-specific satisfaction material; otherwise reassessment must use the proper statut...
Credit-note turnover adjustments preserve inverted-duty refunds, while ministerial re-computation does not constitute an impermissible appellate reman...
Page of 4915
Press 'Enter' after typing page number.
1161 to 1180 of 98288 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
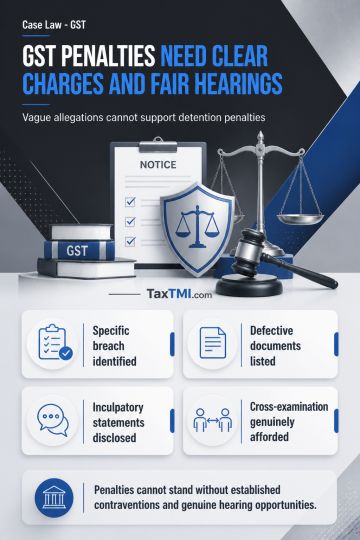
GST detention penalties under section 129 require a pleaded and established contravention of the Act or Rules. A show-cause notice must identify the defective documents and the precise legal provision allegedly breached; a vague allegation of diversion or unloading at an undeclared destination is insufficient. Reliance on inculpatory statements requires their disclosure, and an offered personal hearing and cross-examination opportunity must be genuinely afforded before adjudication. Appellate review must address material natural-justice objections and identify the statutory contravention rather than rely on route or invoicing observations alone.
GST detention penalties under section 129 require a pleaded and established contravention of the Act or Rules. A show-cause notice must identify the defective documents and the precise legal provision allegedly breached; a vague allegation of diversion or unloading at an undeclared destination is insufficient. Reliance on inculpatory statements requires their disclosure, and an offered personal hearing and cross-examination opportunity must be genuinely afforded before adjudication. Appellate review must address material natural-justice objections and identify the statutory contravention rather than rely on route or invoicing observations alone.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915