E-filing system failure permits exclusion of affected time in insolvency appeals, preventing tribunal technology defects from defeating timely filings...
Pre-existing disputes over outcome-based professional fees can bar Section 9 insolvency proceedings where contractual entitlement requires investigati...
Corresponding scheduled offences preserve money-laundering jurisdiction despite repeal of the central corruption provision where conduct remains cover...
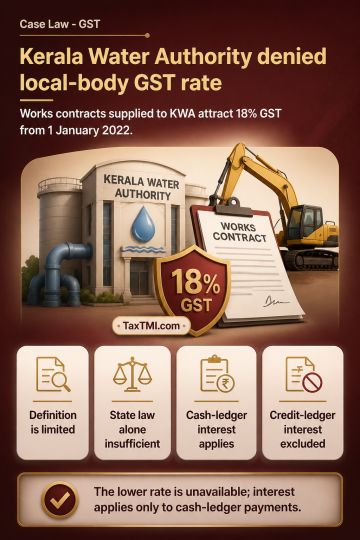
GST local-authority status is confined to bodies expressly enumerated in the CGST/KGST definition; a statutory body is not included merely because its constituting State law deems it a local authority. Accordingly, works contract services supplied to Kerala Water Authority attract GST at 18% from 1 January 2022 rather than the concessional local-authority rate. On delayed differential GST, interest applies only to the portion discharged through the electronic cash ledger, not to the portion paid through the electronic credit ledger.
GST local-authority status is confined to bodies expressly enumerated in the CGST/KGST definition; a statutory body is not included merely because its constituting State law deems it a local authority. Accordingly, works contract services supplied to Kerala Water Authority attract GST at 18% from 1 January 2022 rather than the concessional local-authority rate. On delayed differential GST, interest applies only to the portion discharged through the electronic cash ledger, not to the portion paid through the electronic credit ledger.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915