Capital-gains exemption for charitable trusts extends to qualifying fixed deposits, while unrecoverable TDS write-offs may constitute income applicati...
India-UK treaty characterisation of telecom-service receipts as business profits withstands unilateral domestic-law amendments for Indian tax purposes...
Transfer-pricing reimbursement adjustments require uncontrolled comparables and cannot become expense-genuineness reviews, resulting in deletion of th...
Food import sampling requirements support provisional release where unseized consignments conform to standards and raw areca classification is unestab...
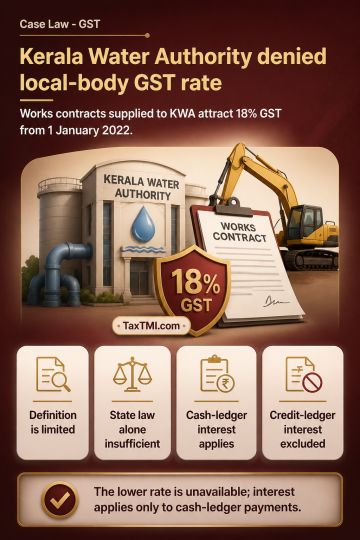
GST local-authority status is confined to bodies expressly enumerated in the CGST/KGST definition; a statutory body is not included merely because its constituting State law deems it a local authority. Accordingly, works contract services supplied to Kerala Water Authority attract GST at 18% from 1 January 2022 rather than the concessional local-authority rate. On delayed differential GST, interest applies only to the portion discharged through the electronic cash ledger, not to the portion paid through the electronic credit ledger.
GST local-authority status is confined to bodies expressly enumerated in the CGST/KGST definition; a statutory body is not included merely because its constituting State law deems it a local authority. Accordingly, works contract services supplied to Kerala Water Authority attract GST at 18% from 1 January 2022 rather than the concessional local-authority rate. On delayed differential GST, interest applies only to the portion discharged through the electronic cash ledger, not to the portion paid through the electronic credit ledger.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915