Suspension of insolvency professional registration prevents continued Resolution Professional appointments and restricts interim stays that effectivel...
Original works exemption for railway contracts depends on actual integrated construction scope, while accessible tax data defeats suppression allegati...
Survey surrender characterisation determines whether mixed excess stock and business-linked cash face normal taxation or special deemed-income taxatio...
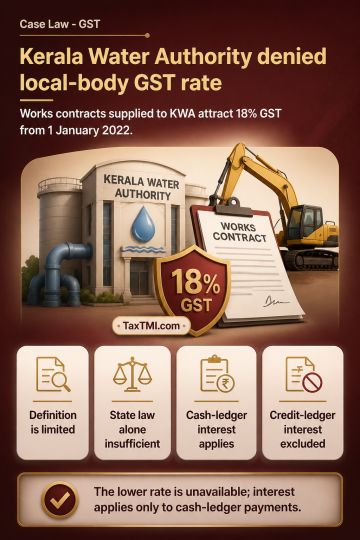
GST local-authority status is confined to bodies expressly enumerated in the CGST/KGST definition; a statutory body is not included merely because its constituting State law deems it a local authority. Accordingly, works contract services supplied to Kerala Water Authority attract GST at 18% from 1 January 2022 rather than the concessional local-authority rate. On delayed differential GST, interest applies only to the portion discharged through the electronic cash ledger, not to the portion paid through the electronic credit ledger.
GST local-authority status is confined to bodies expressly enumerated in the CGST/KGST definition; a statutory body is not included merely because its constituting State law deems it a local authority. Accordingly, works contract services supplied to Kerala Water Authority attract GST at 18% from 1 January 2022 rather than the concessional local-authority rate. On delayed differential GST, interest applies only to the portion discharged through the electronic cash ledger, not to the portion paid through the electronic credit ledger.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918