Head Office cost allocation requires prescribed transfer-pricing methods; treaty ceilings bar surcharge and cess, while duplicate taxation is excluded...
Cost-to-cost reimbursement of seconded employees is not service consideration; transfer-pricing markup was deleted and amalgamation amortisation allow...
Crystallisation of liability supports prior-period expense deduction, while functionally distinct divisions require separate transfer-pricing benchmar...
Functional comparability under TNMM requires transaction-specific FAR analysis before benchmarking business-support services provided to associated en...
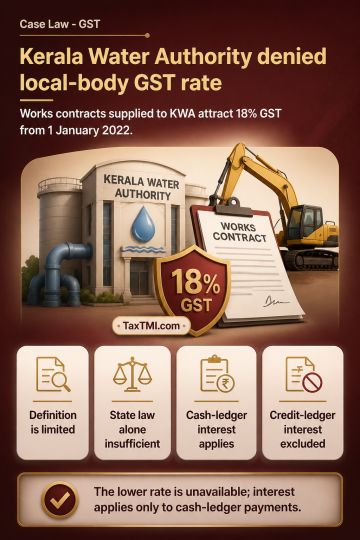
GST local-authority status is confined to bodies expressly enumerated in the CGST/KGST definition; a statutory body is not included merely because its constituting State law deems it a local authority. Accordingly, works contract services supplied to Kerala Water Authority attract GST at 18% from 1 January 2022 rather than the concessional local-authority rate. On delayed differential GST, interest applies only to the portion discharged through the electronic cash ledger, not to the portion paid through the electronic credit ledger.
GST local-authority status is confined to bodies expressly enumerated in the CGST/KGST definition; a statutory body is not included merely because its constituting State law deems it a local authority. Accordingly, works contract services supplied to Kerala Water Authority attract GST at 18% from 1 January 2022 rather than the concessional local-authority rate. On delayed differential GST, interest applies only to the portion discharged through the electronic cash ledger, not to the portion paid through the electronic credit ledger.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915