Delayed judgment pronouncement alone does not invalidate Tribunal orders, while rectification cannot reopen evidence or negate confiscation-related pe...
Agricultural-land reinvestment qualifies when transfer consideration precedes replacement purchase, while unexamined claims may be reassessed on escap...
Bona fide public fixed-deposit explanations prevent concealment penalties where unexplained-credit additions lack independent evidence of undisclosed ...
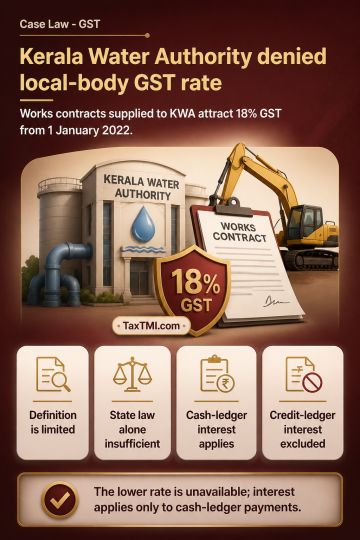
GST local-authority status is confined to bodies expressly enumerated in the CGST/KGST definition; a statutory body is not included merely because its constituting State law deems it a local authority. Accordingly, works contract services supplied to Kerala Water Authority attract GST at 18% from 1 January 2022 rather than the concessional local-authority rate. On delayed differential GST, interest applies only to the portion discharged through the electronic cash ledger, not to the portion paid through the electronic credit ledger.
GST local-authority status is confined to bodies expressly enumerated in the CGST/KGST definition; a statutory body is not included merely because its constituting State law deems it a local authority. Accordingly, works contract services supplied to Kerala Water Authority attract GST at 18% from 1 January 2022 rather than the concessional local-authority rate. On delayed differential GST, interest applies only to the portion discharged through the electronic cash ledger, not to the portion paid through the electronic credit ledger.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915