E-filing system failure permits exclusion of affected time in insolvency appeals, preventing tribunal technology defects from defeating timely filings...
Pre-existing disputes over outcome-based professional fees can bar Section 9 insolvency proceedings where contractual entitlement requires investigati...
Corresponding scheduled offences preserve money-laundering jurisdiction despite repeal of the central corruption provision where conduct remains cover...
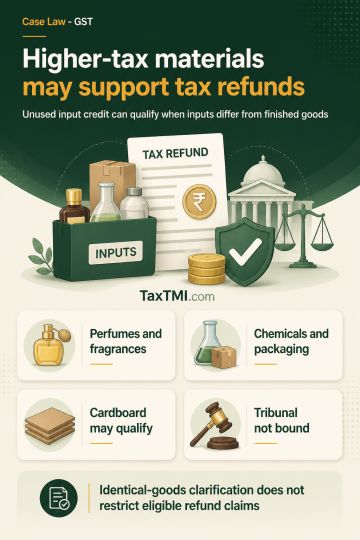
Unutilised input tax credit accumulated from an inverted duty structure is refundable where manufacturing inputs are taxed at a higher rate than the outward supply and are distinct from the finished goods. For Agarbati manufacturing, perfumes, fragrances, chemicals, packaging materials and cardboard qualify as inputs whose higher tax rates may support refund eligibility. A CBIC clarification addressing situations where input and output supplies are the same goods does not restrict such claims. CBIC circulars bind central tax officers but not the Appellate Tribunal, although they may carry persuasive value.
Unutilised input tax credit accumulated from an inverted duty structure is refundable where manufacturing inputs are taxed at a higher rate than the outward supply and are distinct from the finished goods. For Agarbati manufacturing, perfumes, fragrances, chemicals, packaging materials and cardboard qualify as inputs whose higher tax rates may support refund eligibility. A CBIC clarification addressing situations where input and output supplies are the same goods does not restrict such claims. CBIC circulars bind central tax officers but not the Appellate Tribunal, although they may carry persuasive value.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915