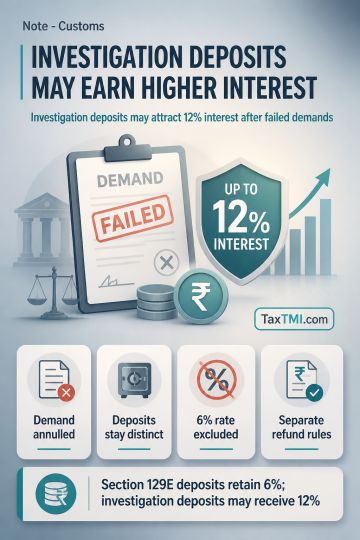
Investigation deposits refunded after failed customs demands fall outside the statutory appellate pre-deposit interest regime and may attract compensa...
Resolution plan finality extinguishes unquantified operational-creditor claims and pending proceedings unless the approved plan expressly preserves th...
Stakeholder-list modification permits liquidators to update entries on new information, subject to notifying the Adjudicating Authority within prescri...
Unutilised input tax credit accumulated from an inverted duty structure is refundable where manufacturing inputs are taxed at a higher rate than the outward supply and are distinct from the finished goods. For Agarbati manufacturing, perfumes, fragrances, chemicals, packaging materials and cardboard qualify as inputs whose higher tax rates may support refund eligibility. A CBIC clarification addressing situations where input and output supplies are the same goods does not restrict such claims. CBIC circulars bind central tax officers but not the Appellate Tribunal, although they may carry persuasive value.
Unutilised input tax credit accumulated from an inverted duty structure is refundable where manufacturing inputs are taxed at a higher rate than the outward supply and are distinct from the finished goods. For Agarbati manufacturing, perfumes, fragrances, chemicals, packaging materials and cardboard qualify as inputs whose higher tax rates may support refund eligibility. A CBIC clarification addressing situations where input and output supplies are the same goods does not restrict such claims. CBIC circulars bind central tax officers but not the Appellate Tribunal, although they may carry persuasive value.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915