Capital Asset Conversion Requires Proven Business Stock Treatment; Paper Consideration in Spousal Flat Transfers Does Not Create Taxable Business Inco...
Human-probability test defeats political donation deduction where banking records mask accommodation-entry fund layering and evidence shows non-genuin...
Commercial property status protects capital-gains exemption when residential-house ownership limits are tested, while agricultural-land character gove...
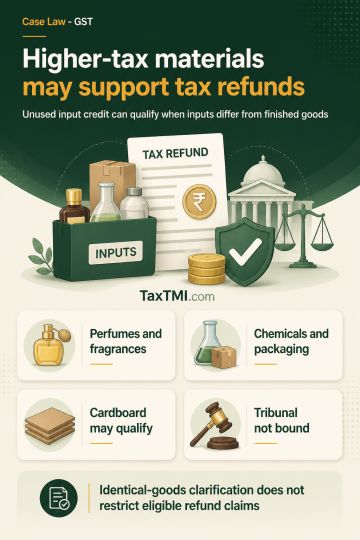
Unutilised input tax credit accumulated from an inverted duty structure is refundable where manufacturing inputs are taxed at a higher rate than the outward supply and are distinct from the finished goods. For Agarbati manufacturing, perfumes, fragrances, chemicals, packaging materials and cardboard qualify as inputs whose higher tax rates may support refund eligibility. A CBIC clarification addressing situations where input and output supplies are the same goods does not restrict such claims. CBIC circulars bind central tax officers but not the Appellate Tribunal, although they may carry persuasive value.
Unutilised input tax credit accumulated from an inverted duty structure is refundable where manufacturing inputs are taxed at a higher rate than the outward supply and are distinct from the finished goods. For Agarbati manufacturing, perfumes, fragrances, chemicals, packaging materials and cardboard qualify as inputs whose higher tax rates may support refund eligibility. A CBIC clarification addressing situations where input and output supplies are the same goods does not restrict such claims. CBIC circulars bind central tax officers but not the Appellate Tribunal, although they may carry persuasive value.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915