Blocked input tax credit for resort construction remains unavailable; interest follows actual utilisation, while delayed payment attracts statutory pe...
Duplicate PAN allocation requires record verification and deactivation reasons before assessment-related transactions can be attributed to an assessee...
Faceless assessment safeguards require requested personal hearings and adequate final show-cause response time, failing which reassessment is required...
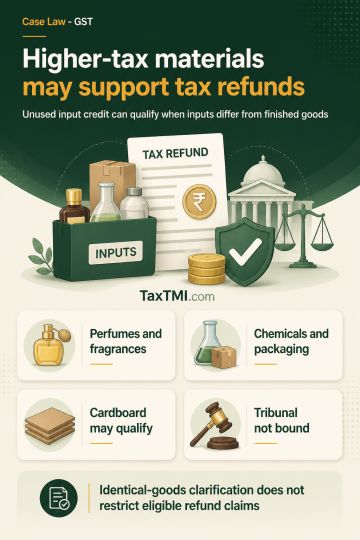
Unutilised input tax credit accumulated from an inverted duty structure is refundable where manufacturing inputs are taxed at a higher rate than the outward supply and are distinct from the finished goods. For Agarbati manufacturing, perfumes, fragrances, chemicals, packaging materials and cardboard qualify as inputs whose higher tax rates may support refund eligibility. A CBIC clarification addressing situations where input and output supplies are the same goods does not restrict such claims. CBIC circulars bind central tax officers but not the Appellate Tribunal, although they may carry persuasive value.
Unutilised input tax credit accumulated from an inverted duty structure is refundable where manufacturing inputs are taxed at a higher rate than the outward supply and are distinct from the finished goods. For Agarbati manufacturing, perfumes, fragrances, chemicals, packaging materials and cardboard qualify as inputs whose higher tax rates may support refund eligibility. A CBIC clarification addressing situations where input and output supplies are the same goods does not restrict such claims. CBIC circulars bind central tax officers but not the Appellate Tribunal, although they may carry persuasive value.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918