Head Office cost allocation requires prescribed transfer-pricing methods; treaty ceilings bar surcharge and cess, while duplicate taxation is excluded...
Cost-to-cost reimbursement of seconded employees is not service consideration; transfer-pricing markup was deleted and amalgamation amortisation allow...
Crystallisation of liability supports prior-period expense deduction, while functionally distinct divisions require separate transfer-pricing benchmar...
Functional comparability under TNMM requires transaction-specific FAR analysis before benchmarking business-support services provided to associated en...
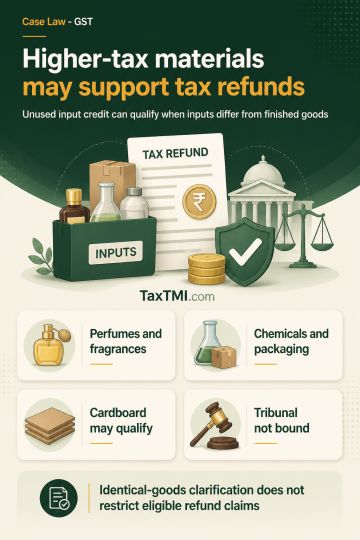
Unutilised input tax credit accumulated from an inverted duty structure is refundable where manufacturing inputs are taxed at a higher rate than the outward supply and are distinct from the finished goods. For Agarbati manufacturing, perfumes, fragrances, chemicals, packaging materials and cardboard qualify as inputs whose higher tax rates may support refund eligibility. A CBIC clarification addressing situations where input and output supplies are the same goods does not restrict such claims. CBIC circulars bind central tax officers but not the Appellate Tribunal, although they may carry persuasive value.
Unutilised input tax credit accumulated from an inverted duty structure is refundable where manufacturing inputs are taxed at a higher rate than the outward supply and are distinct from the finished goods. For Agarbati manufacturing, perfumes, fragrances, chemicals, packaging materials and cardboard qualify as inputs whose higher tax rates may support refund eligibility. A CBIC clarification addressing situations where input and output supplies are the same goods does not restrict such claims. CBIC circulars bind central tax officers but not the Appellate Tribunal, although they may carry persuasive value.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915