Business expenditure and depreciation rules allow operational outgoings while limiting disallowances for personal elements and unsupported third-party...
Compromise-and-arrangement extensions may accommodate debt assignment where creditor commercial judgment supports value maximisation and avoids proced...
Delayed-payment surcharge is not taxable tolerance consideration where it penalises default, while meter testing follows electricity distribution trea...
Sufficient cause for delayed revenue income-tax appeals requires bona fides, due diligence and a credible explanation; otherwise limitation bars appea...
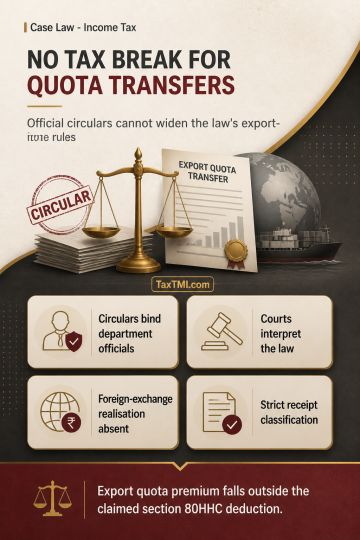
Export quota premium is not equivalent to export-incentive receipts eligible for deduction under section 80HHC. Administrative circulars bind departmental authorities but cannot bind courts, override statutory language, or displace judicial interpretation. Equating premium from the transfer of export quota with receipts covered by the specified export-incentive provisions would create an impermissible legal fiction, particularly because such premium lacks characteristics of those receipts, including foreign-exchange realisation. Tax deductions must be construed strictly by reference to income derived and the statutory classification of eligible receipts; export quota premium therefore falls outside the claimed deduction.
Export quota premium is not equivalent to export-incentive receipts eligible for deduction under section 80HHC. Administrative circulars bind departmental authorities but cannot bind courts, override statutory language, or displace judicial interpretation. Equating premium from the transfer of export quota with receipts covered by the specified export-incentive provisions would create an impermissible legal fiction, particularly because such premium lacks characteristics of those receipts, including foreign-exchange realisation. Tax deductions must be construed strictly by reference to income derived and the statutory classification of eligible receipts; export quota premium therefore falls outside the claimed deduction.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916