Transfer-pricing aggregation of distinct support-service and subcontract transactions was rejected, while debt-free receivables attracted no notional ...
Customs exemptions cover photovoltaic assembly machinery and PVF backsheets, while fully declared cleared imports may avoid confiscation and penalties...
Specific tariff classification for LCD devices overrides treatment as electricity-meter parts, defeating differential duty, extended limitation, and p...
Stayed disciplinary punishment does not establish unfitness for insolvency professional registration; reconsideration must disregard mere pendency of ...
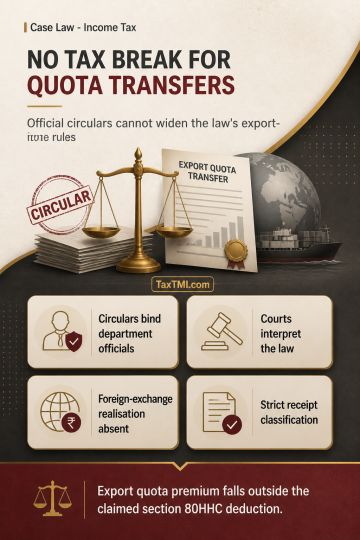
Export quota premium is not equivalent to export-incentive receipts eligible for deduction under section 80HHC. Administrative circulars bind departmental authorities but cannot bind courts, override statutory language, or displace judicial interpretation. Equating premium from the transfer of export quota with receipts covered by the specified export-incentive provisions would create an impermissible legal fiction, particularly because such premium lacks characteristics of those receipts, including foreign-exchange realisation. Tax deductions must be construed strictly by reference to income derived and the statutory classification of eligible receipts; export quota premium therefore falls outside the claimed deduction.
Export quota premium is not equivalent to export-incentive receipts eligible for deduction under section 80HHC. Administrative circulars bind departmental authorities but cannot bind courts, override statutory language, or displace judicial interpretation. Equating premium from the transfer of export quota with receipts covered by the specified export-incentive provisions would create an impermissible legal fiction, particularly because such premium lacks characteristics of those receipts, including foreign-exchange realisation. Tax deductions must be construed strictly by reference to income derived and the statutory classification of eligible receipts; export quota premium therefore falls outside the claimed deduction.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915