Suspension of insolvency professional registration prevents continued Resolution Professional appointments and restricts interim stays that effectivel...
Original works exemption for railway contracts depends on actual integrated construction scope, while accessible tax data defeats suppression allegati...
Survey surrender characterisation determines whether mixed excess stock and business-linked cash face normal taxation or special deemed-income taxatio...
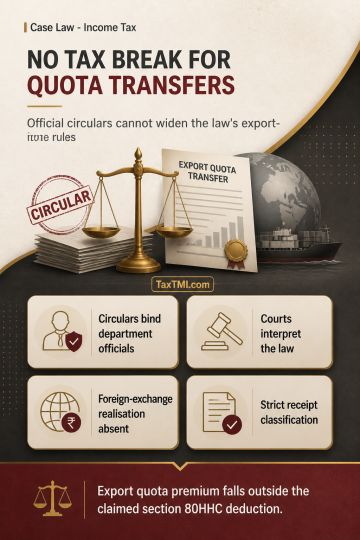
Export quota premium is not equivalent to export-incentive receipts eligible for deduction under section 80HHC. Administrative circulars bind departmental authorities but cannot bind courts, override statutory language, or displace judicial interpretation. Equating premium from the transfer of export quota with receipts covered by the specified export-incentive provisions would create an impermissible legal fiction, particularly because such premium lacks characteristics of those receipts, including foreign-exchange realisation. Tax deductions must be construed strictly by reference to income derived and the statutory classification of eligible receipts; export quota premium therefore falls outside the claimed deduction.
Export quota premium is not equivalent to export-incentive receipts eligible for deduction under section 80HHC. Administrative circulars bind departmental authorities but cannot bind courts, override statutory language, or displace judicial interpretation. Equating premium from the transfer of export quota with receipts covered by the specified export-incentive provisions would create an impermissible legal fiction, particularly because such premium lacks characteristics of those receipts, including foreign-exchange realisation. Tax deductions must be construed strictly by reference to income derived and the statutory classification of eligible receipts; export quota premium therefore falls outside the claimed deduction.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918