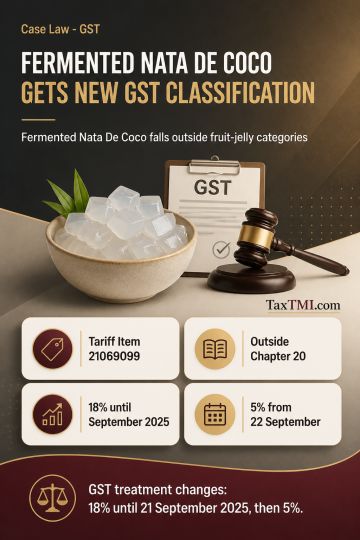
Residual food-preparation classification places fermented Nata De Coco outside fruit-jelly categories, changing its GST treatment across notified peri...
Settlement application eligibility requires a pending assessment when filed, preventing an extra prior-eligibility condition from blocking considerati...
Reassessment for unreturned property sales survives where transfer information, non-filing, and unsupported exemption claims establish a prima facie l...
Profit-element taxation limits additions for unaccounted flat-sale receipts and grey-market purchases, while reliable search records support partial a...
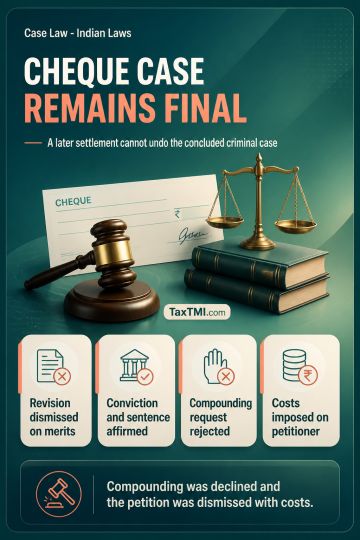
Post-conviction compounding of a cheque dishonour offence is unavailable once criminal revision has been dismissed on merits and has affirmed the conviction and sentence. Finality prevents inherent jurisdiction from being used to review or nullify a concluded criminal adjudication, and a subsequent settlement cannot indirectly reopen the conviction. Authorities permitting compounding were distinguishable on the stated facts. The petition seeking compounding was not maintainable; compounding was declined and the petition was dismissed with costs.
Post-conviction compounding of a cheque dishonour offence is unavailable once criminal revision has been dismissed on merits and has affirmed the conviction and sentence. Finality prevents inherent jurisdiction from being used to review or nullify a concluded criminal adjudication, and a subsequent settlement cannot indirectly reopen the conviction. Authorities permitting compounding were distinguishable on the stated facts. The petition seeking compounding was not maintainable; compounding was declined and the petition was dismissed with costs.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915