Centralised assessment transfers after searches coordinate connected investigations without finally determining the assessee's tax liability or assess...
Unsigned third-party records cannot establish on-money payments without corroboration and cross-examination, requiring deletion of the related additio...
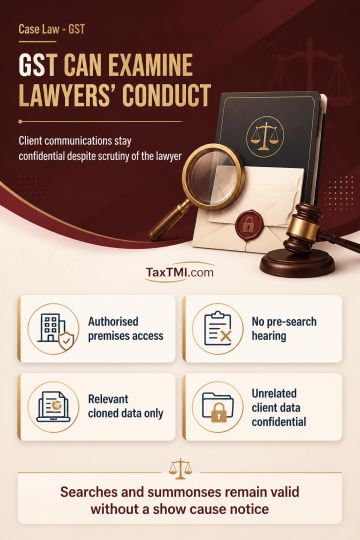
GST search powers may extend to an advocate's cabin and electronic records within authorised premises where recorded reasons support statutory satisfaction; a pre-search hearing is not required. Advocate-client privilege protects client communications and confidentiality, but does not immunise an advocate's own conduct from investigation. Only cloned electronic data relevant to the investigation may be used, and unrelated client material must remain confidential. Sealed investigative records need not be disclosed while investigation continues because disclosure may expose its course and witness statements. Absence of a show cause notice at the investigation stage does not invalidate searches or summonses.
GST search powers may extend to an advocate's cabin and electronic records within authorised premises where recorded reasons support statutory satisfaction; a pre-search hearing is not required. Advocate-client privilege protects client communications and confidentiality, but does not immunise an advocate's own conduct from investigation. Only cloned electronic data relevant to the investigation may be used, and unrelated client material must remain confidential. Sealed investigative records need not be disclosed while investigation continues because disclosure may expose its course and witness statements. Absence of a show cause notice at the investigation stage does not invalidate searches or summonses.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI